Best High-Risk Homeowners Insurance for 2026


- State Farm is our top pick for high-risk insurance because of its favorable rates, wide availability and lenient terms for pet owners.
- Homeowners might need a high-risk insurance policy if they have older homes, credit issues, certain dog breeds or properties in areas prone to weather damage.
- Other insurers like Allstate, Progressive and American Family also offer solid options for high-risk homes.
High-risk homeowners insurance often becomes necessary for many homeowners, such as those with homes that are prone to extreme weather-related damage, those who own older properties, properties with “attractive nuisances” like a swimming pool or homeowners who have poor credit.
High-risk home insurance usually costs more or may offer less coverage than a standard home insurance policy. That’s why it’s important to work with an insurance company that offers policies and terms that can meet your specific risk level.
Home insurance rates are on the rise because of rising construction costs, inflation and increasingly severe natural disasters. Add to that needing to get high-risk insurance, and the cost of insuring a home can grow even more. Fortunately, some insurers — like the ones we highlight below — specialize in policies that ensure ample coverage for those situations.
Our top picks were chosen from a list of 10 top national home insurance companies with publicly available rates. In addition to the suggestions below, it’s always a good practice to shop around, especially among regional insurance companies, since rates can vary widely based on where you live for this kind of insurance.
Best overall: State Farm
Why we chose it: State Farm is the nation’s largest insurance company with strong overall ratings and some of the cheapest policies, with rates typically 13% less than the national average. It also offers benefits for homeowners who could potentially be considered high-risk elsewhere. For instance, State Farm doesn’t limit coverage based on your dog’s breed, and it offers discounts for impact-resistent roofing and wind and wildfire mitigation.
Who it’s best for: Homeowners looking for affordable coverage for certain high-risk properties
Best for discounts: Allstate
Why we chose it: Allstate is another well-known national insurance carrier with premiums lower than the national average. High-risk homeowners may be able to lower their premiums by qualifying for one of Allstate’s eight home insurance discounts.
Who it’s best for: Homeowners who can qualify for some of the available discounts
Best for vacant properties: American Family
Why we chose it: In addition to American Family’s excellent customer service ratings, American Family sells 12-month home insurance policies for vacant homes, while most other companies only offer three- or six-month policies. There are also opportunities to qualify for discounts by having smart home technology or water leak detectors that keep tabs on the property when you’re not there.
Who it’s best for: Homeowners who cannot move into a new home right away or who inherit a home
Compare home insurance companies
Here are some general homeowners insurance ratings for the top national home insurers we looked at for this report. How we determined our LendingTree rating is explained below.
| Company | LendingTree score* | Complaint rating* | |
|---|---|---|---|
 | AAA | 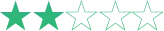 | N/A |
 | Allstate | 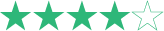 | 1.2 |
 | American Family | | 0.4 |
 | Chubb | | <0.1 |
 | Farmers | 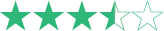 | 0.7 |
 | Nationwide | | 1.2 |
 | Progressive | | 1.8 |
 | State Farm | | 1.4 |
 | Travelers | | 0.7 |
 | USAA* | | 0.5 |
High-risk homeowners insurance is for people who have a higher risk of filing a claim than others. This can include people who live in high-risk homes (based on location, home age/condition or extreme weather risk) and those who may be considered high-risk homeowners because of past insurance claim history, poor credit or, with some insurance companies, owning a potentially dangerous dog breed.
Who needs high-risk home insurance?
If an insurance company determines that you have a high risk of filing a home insurance claim, it may decide not to offer you standard insurance. In that case, you will need to look for high-risk home insurance.
This can happen to homeowners who have high-risk properties because of location (such as being in an area that often gets hit with tornadoes or floods) or property condition, or who pose a higher risk to insurers based on personal financial and credit history.
These policies typically have higher rates in order to offset the additional risk.
Some common homeowner types who often pay high-risk home insurance premiums include:
Homeowners with bad credit
One of the factors that home insurance companies use to determine rates is credit history. Credit scores and past payment behaviors often indicate which homeowners are more likely to miss payments or file claims.
Credit scores, such as the FICO scoring model, are based on factors like carrying high balances on credit cards and loans, missing payments, defaulting on debts or having accounts in collections.
Homeowners with poor credit — which generally means they have credit scores below 580 — are more likely to be offered higher insurance rates. However, some states restrict or prohibit the use of credit scores in setting home insurance rates or offering a new policy, including:
- California
- Maryland
- Massachusetts
- Michigan
- Oregon
Homeowners with dogs
A standard insurance policy often covers any injuries if a homeowner’s dog bites someone. However, some insurers deem certain breeds a higher bite risk and may exclude them from coverage. These may include:
- Wolf-dog hybrids
- American bulldogs
- Cane corsos
- Chow chows
- Doberman pinschers
- Pit bulls
- Presa Canarios
- Mastiffs
- Rottweilers
If you own one of these breeds, ask your home insurance company if your policy covers you. Keep in mind that the situation can be more complex (and rates can be higher) if your dog has a bite history. If your insurer won’t cover your dog, then you may need a high-risk policy.
Vacant or unoccupied homes
Vacant homes refer to furnished properties that don’t have any residents living there, while unoccupied homes are usually empty of belongings and appliances are turned off. Homes are considered either vacant or unoccupied when no one has been living in them for more than 30 days.
When homeowners live in a property, they are more likely to notice and address small problems such as a slow leak before they can cause more damage. They can also call for emergency services if they smell gas or if a fire breaks out.
In vacant or unoccupied homes, those situations are more likely to go unnoticed. Homes that are vacant or unoccupied usually have higher home insurance rates because they are more at risk than occupied homes.
Homeowners with ‘attractive nuisances’
An attractive nuisance is anything that can increase risk because it might attract others onto the property and create an unsafe situation or hazardous condition.
For example, having a swimming pool or a trampoline in your yard could be attractive to young children who might wander or be invited onto your property.
Home insurance companies have found that such “nuisances” could increase the chance of a personal injury claim and impose higher rates or exclude the attractive nuisance from coverage as a result. In extreme cases, homeowners could even be denied coverage.
Fair Access to Insurance Requirements (FAIR) plans are state-run programs that ensure homeowners who can’t find high-risk home coverage can access an insurer of last resort. These are available in more than half of states, though they may go by a different name.
How do I reduce my home insurance risk?
While some external factors like home location may be out of your control, there are some ways you can reduce your need for high-risk home insurance.
Keep in mind that it’s always a good idea to compare quotes from several companies since some insurers are more lenient than others when it comes to certain factors.
Improve your credit score
Bad credit is a high-risk factor that you can control, though it can take some time to see improvements. Focus on the most impactful credit score factors:
- Always pay bills on time
- Maintain low credit card balances
- Check your credit report for errors
Over time, committing to good credit habits like these can help raise your score.
Restrict attractive nuisances
If insurance companies are charging you higher rates because you have attractive nuisances on your property, these mitigations may help:
- Keep a locked fence around your pool.
- Put a safety net barrier around your trampoline.
- Remove slip hazards from around the pool.
- Lock up pool cleaning chemicals.
- Install a security system and/or floodlights around your pool.
Compare home insurance providers
If your home insurance company raises your rates due to a high-risk issue, or even cancels your coverage, take the opportunity to compare home insurance quotes from multiple companies.
Home insurance companies use different methods for evaluating risk and determining rates. Comparing quotes from several insurers side by side can give you a better chance of finding the most affordable policy for your situation and budget.
Talk to your neighbors
If your neighborhood is flagged as high-risk because of extreme weather or a high crime rate, ask your neighbors for their home insurance company recommendations. They are likely in the same situation as you and may help you find coverage. For example, they may know of a regional insurer that specializes in the type of coverage you need.
How LendingTree helps you find the right policy
Shopping for home insurance isn’t always straightforward — especially when availability and pricing can vary widely. LendingTree makes it easier by helping you explore options from multiple insurers, so you can find coverage that fits your home, location and budget.
How it works
Tell us about your home
Answer a few quick questions about your home, location and coverage needs.
Compare options from insurers
See quotes and typical rates from insurers that offer coverage in your area.
Choose the right policy
Review your options and pick the coverage that fits your needs and budget.
Frequently asked questions
Some home insurance companies may deny you coverage because your dog’s breed might be flagged as a high bite risk. However, several states prohibit insurers from denying coverage just for this reason. Even if an insurance company offers you a standard policy, they may exclude dog bite injuries from your liability coverage or you might have to pay a higher premium.
A high-risk home insurance policy is usually more expensive than a standard one, but by how much depends on the reason for the high risk and the insurance options available. For example, coverage for homes at risk for extreme weather or in poor condition because of age are likely to be more costly than for a homeowner whose high-risk situation is having a swimming pool or less-than-stellar credit.
If you can’t get high-risk homeowners insurance, check whether your state offers a FAIR plan, which gives you access to a state-backed insurer of last resort. If not, you can try working with a broker who may be able to help you find a specialized policy for your needs. You can also try to fix or reduce the high-risk factor, such as by making property improvements or raising your credit score.
Methodology
The recommendations above are based on publicly available information from the insurance companies, as well as the overall ratings of the insurance company (LendingTree and Complaint Index scores).
For third-party customer service ratings, we included NAIC’s Complaint Index scores and financial strength ratings from AM Best. NAIC Complaint Index scores are used to determine how satisfied customers are with their claims, while financial strength ratings from AM Best reflect the ability to pay out claims.
How we create LendingTree ratings
LendingTree’s team of insurance experts evaluates insurance companies across several categories, including average rates, discounts, coverage options, third-party customer service ratings and app/website experience. We use this information to create LendingTree ratings, which help us identify and recommend the best insurance companies for consumers.
See our home insurance ratings methodology and full editorial guidelines for further details.
*USAA is primarily only available to current and former members of the military and their families.