Best Personal Loans With a Cosigner in 2026: Compare 5 Lenders
A cosigner or co-borrower can help you qualify for a personal loan or receive better terms


Advertising Disclosures
Loading Disclosures…
Quick answer: A cosigner personal loan lets someone with stronger credit or income guarantee your loan without receiving any of the money, improving your odds of approval and often lowering your rate. A co-borrower operates similarly, but has access to the loan money. Across LendingTree’s marketplace of 300+ lenders, many offer cosigner or co-borrower loans. Compare the best cosigner and co-borrower loans, based on our independent rating system that considers what borrowers actually want, below.
| Lender | User rating | Best for | APR | Min. credit score | See Results |
|---|---|---|---|---|---|

|
Debt consolidation cosigner loans | 5.96% to 35.99% | 600 | ||

|
Cosigner loans with membership benefits | 6.39% to 17.99% (with autopay) | Not specified | ||

|
Peer-to-peer co-borrower loans | 8.99% to 35.99% | 600 | ||

|
Fast online loans with a co-borrower | 6.99% to 35.49% (with discounts) | 600 | ||

|
Multiple discounts on co-borrower loans | 7.74% to 35.99% (with discounts) | 600 |
Compare the best personal loans with a cosigner or co-borrower

Best for: Debt consolidation co-borrower loans – Happen Bank
- APR
- 5.96% to 35.99%
- Amount
- $1k – $75k
- Term
- 24 to 84 months
- Origination fee
- 0.00% – 8.00%
- Min. credit score
- 600
- Low interest rates
- Can pay current creditors off directly
- Can receive funds within 24 hours of approval
- Allows you to change the payment due date
- Offers large loan amounts
- May charge an origination fee
- May not qualify with bad credit
Happen Bank (formerly LendingClub) can send your loan funds directly to any current creditors if you get a debt consolidation loan. After you’re approved, you may get your money within 24 hours.
Keep in mind that Happen Bank may charge you an origination fee (0.00% – 8.00%), and you may not qualify if you have bad credit. However, having a co-borrower can improve your chances of getting approved.
To be eligible for a Happen Bank personal loan, you must meet the following requirements:
- Age: Be at least 18 years old
- Citizenship: Be a U.S. citizen or permanent resident
- Administrative: Have a verifiable bank account
- Credit score: 600+
Best for: Co-borrower loans with membership benefits – PenFed Credit Union
- APR (with autopay)
- 6.39% to 17.99%
- Amount
- $600 – $50k
- Term
- 12 to 60 months
- Origination fee
- None
- Min. credit score
- Not specified
- Small loan amounts
- Low maximum APR
- No origination fee
- Autopay rate discount
- Must be a member of the credit union
- Doesn’t specify a minimum credit score
Many personal lenders charge maximum APRs close to 36%. Because it’s a federal credit union, PenFed Credit Union stands out for capping its rates at 17.99%.
Borrowers can take out as little as $600 from PenFed and the lender doesn’t charge origination fees, so you can borrow what you need instead of budgeting for a fee. To get a personal loan, you will have to become a PenFed member, but anyone can join.
To qualify for a PenFed Credit Union loan, you must meet the following requirements:
- Membership: PenFed Credit Union membership (anyone can apply)
- Administrative: Open up PenFed Credit Union savings account with $5 deposit; may need to submit documents to verify your identity and income
Best for: Peer-to-peer co-borrower loans – Prosper
- APR
- 8.99% to 35.99%
- Amount
- $2k – $50k
- Term
- 24 to 72 months
- Origination fee
- 1.00% – 9.99%
- Min. credit score
- 600
- Offers a robust mobile app
- Provides online pre-approval
- Offers FICO Score insights
- Charges an origination fee on all loans
- Doesn’t allow cosigners, only co-borrowers
- Not available in all states
Prosper offers peer-to-peer loans, meaning the loans are offered by an individual investor instead of a bank or lender, which is how loans are traditionally funded. This can make it easier to qualify for a personal loan.
Prosper also has a dedicated personal loan app, which may appeal to consumers who would like easy mobile access to their accounts. However, Prosper charges origination fees on all its loans and isn’t available in all 50 states.
To get a loan with Prosper, you must meet the following requirements:
- Age: Be 18 or older
- Administrative: Have a U.S. bank account and Social Security number
- Residency: Must live in an eligible U.S. state (Prosper operates in most states, with only a small number of states excluded)
- Credit score: 600+
Best for: Fast online loans with a co-borrower – SoFi
- APR (with discounts)
- 6.99% to 35.49%
Terms and conditions apply. SOFI RESERVES THE RIGHT TO MODIFY OR DISCONTINUE PRODUCTS AND BENEFITS AT ANY TIME WITHOUT NOTICE. To qualify, a borrower must be a U.S. citizen or other eligible status, be residing in the U.S., and meet SoFi’s underwriting requirements. Not all borrowers receive the lowest rate. Lowest rates reserved for the most creditworthy borrowers. If approved, your actual rate will be within the range of rates at the time of application and will depend on a variety of factors, including term of loan, evaluation of your creditworthiness, income, and other factors. If SoFi is unable to offer you a loan but matches you for a loan with a participating bank, then your rate may be outside the range of rates listed above. Rates and Terms are subject to change at any time without notice. SoFi Personal Loans can be used for any lawful personal, family, or household purposes and may not be used for post-secondary education expenses. Minimum loan amount is $5,000. The average of SoFi Personal Loans funded in 2025 was around $32K. Based on loans funded from 1/1/2025-12/31/2025. Information current as of 10/02/26. SoFi Personal Loans originated by SoFi Bank, N.A. Member FDIC. NMLS #696891 (www.nmlsconsumeraccess.org). See SoFi.com/legal for state-specific license details. See SoFi.com/eligibility for details and state restrictions. Fixed rates from 6.99% APR to 35.49% APR. APR reflect the 0.25% autopay interest rate discount and a 0.25% member rate discount. SoFi Platform personal loans are made either by SoFi Bank, N.A. or , Cross River Bank, a New Jersey State Chartered Commercial Bank, operating from its Delaware branch, Member FDIC, Equal Housing Lender. SoFi may receive compensation if you take out a loan originated by Cross River Bank. These rate ranges are current as of 09/14/26 and are subject to change without notice. Not all rates and amounts available in all states. See SoFi Personal Loan eligibility details at https://www.sofi.com/eligibilitycriteria/#eligibility-personal. Not all applicants qualify for the lowest rate. Lowest rates reserved for the most creditworthy borrowers. Your actual rate will be within the range of rates listed above and will depend on a variety of factors, including evaluation of your credit worthiness, income, and other factors. Loan amounts range from $5,000– $100,000. The APR is the cost of credit as a yearly rate and reflects both your interest rate and an origination fee of 9.99% of your loan amount for Cross River Bank originated loans which will be deducted from any loan proceeds you receive and for SoFi Bank originated loans have an origination fee of 0%-7%, will be deducted from any loan proceeds you receive. Autopay Discount: The SoFi 0.25% autopay interest rate reduction requires you to make monthly payments using SoFi’s automatic monthly deduction from a savings or checking account. The discount will discontinue and be lost when you do not have autopay enabled. You’re not required to set up autopay to obtain this loan. Member Rate Discount: To be eligible for an additional 0.25% interest rate reduction on a Personal Loan, you must, within 31 days of loan funding, either (1) meet SoFi Plus eligibility criteria, (2) receive an Eligible Direct Deposit into a SoFi Checking or Savings account, or (3) receive at least $5,000 in Qualifying Deposits into a SoFi Checking or Savings account. You must continue to meet at least one of the above eligibility criteria every 31 days to maintain the discount. See the SoFi Plus terms for details on SoFi Plus subscription. For more details on Eligible Direct Deposit or Qualifying Deposits, please see https://www.sofi.com/legal/banking-rate-sheet. Once you become eligible during the initial period, the discount will be removed or reinstated depending on whether the criteria have been met. Each time your loan is re-amortized, your monthly payment amount will change based upon the interest rate that was in place. SoFi reserves the right to modify or terminate this offer at any time for unenrolled participants. You are not required to meet these criteria to be approved for a loan.
- Amount
- $5k – $100k
- Term
- 24 to 84 months
- Origination fee
- 0.00% – 7.00% (optional)
- Min. credit score
- 600
- Has loans up to $100,000
- Offers same-day funding
- Offers a 0.25% autopay discount
- Long repayment terms available
- No required fees
- Only accepts co-borrowers who live with the primary applicant
- Has a high minimum loan amount
- May need to accept an origination fee if you want lower rates
If you need to borrow a large amount of money, SoFi offers loans up to $100,000 for qualified consumers. If you go ahead with a joint loan, note that your SoFi application may take an extra one or two weeks to review. Also, your co-borrower can only apply with you if you live together.
If you want to qualify for lower rates, however, you may have to accept an origination fee.
You must meet the requirements below to get a loan from SoFi:
- Age: Be the age of majority in your state (typically 18)
- Citizenship: Be a U.S. citizen, an eligible permanent resident or a non-permanent resident (a Deferred Action for Childhood Arrivals recipient or asylum-seeker, for instance)
- Employment: Have a job or job offer with a start date within 90 days or have regular income from another source
- Credit score: 600+
Best for: Multiple discounts on co-borrower loans – Upgrade
- APR (with discounts)
- 7.74% to 35.99%
- Amount
- $1k – $50k
- Term
- 24 to 84 months
- Origination fee
- 1.85% – 9.99%
- Min. credit score
- 600
- May provide funds within one business day
- Offers secured and unsecured loans
- Allows online prequalification
- Charges an origination fee
- May charge a high APR of up to 35.99%
If you want to maximize savings on your interest rate, Upgrade may be a good option since they offer multiple rate discounts. If you use autopay or use the loan funds to pay off other debt, Upgrade may cut your rate. A joint loan may also get you a lower rate and qualify you for a higher loan amount.
Unlike some companies, however, Upgrade charges an origination fee on all personal loans.
To qualify for a loan through Upgrade, you must meet the requirements below:
- Age: Be at least 18 years old (19 in some states)
- Citizenship: Be a U.S. citizen, permanent resident or live in the U.S. with a valid visa
- Administrative: Have a valid bank account and email address
- Credit score: 600+
LendingTree reviewed lenders and marketplaces offering cosigner or co-borrower options, then assessed eligibility and access, cost to borrow, loan terms and options and repayment support.
See the full methodology below.
Compare personal loan offers with LendingTree
You’d shop around for flights. Why not your loan? LendingTree makes it easy. Instead of applying to just one lender and hoping for a good rate, see multiple lenders compete for your business — so you can choose the best offer.
Tell us what you need
Take two minutes to tell us who you are and how much money you need. It’s free, simple and secure.
Shop your offers
LendingTree users get 11 personal loan offers on average. Compare your offers side by side to get the best deal.
Get your money
Users could save an average of $1,787
Based on LendingTree’s analysis of personal loan offers from May 2026. Across all credit profiles, choosing the lowest-APR offer instead of the highest-APR offer could save borrowers an average of $1,787 over a 36-month loan. Estimates are based on the average loan amount among borrowers who closed a personal loan during the study period.
How personal loans with a cosigner work
When you apply for a personal loan, the lender will weigh factors such as your credit score, income and debt-to-income (DTI) ratio. If you have a low credit score, a cosigner with a stronger financial profile can help you get approved. Even if you could get approved on your own, a cosigner could help you unlock a lower rate, saving you money over the loan term.
Note that a cosigner on a personal loan is equally responsible for paying back your loan if you’re unable to. The loan and its payment history can also appear on the cosigner’s credit report, not just yours.
A good cosigner is someone with a financial profile that will appeal to a lender. That means a reliable income, a good credit score and a DTI ratio below 36%.
In general, a good credit score is a FICO Score of 670 or higher, but each lender will have its own requirements. On a personal level, a good cosigner is likely someone you trust and who trusts you — typically a family member or friend.
Cosigner vs. co-borrower: What’s the difference?
If you have a co-borrower, the two of you share responsibility for loan payments and can both access funds from the loan as well as any asset purchased with the money. In contrast, a cosigner only becomes responsible for loan payments if the primary borrower falls behind. A cosigner also doesn’t have equal rights to the loan funds.
A personal loan with a co-borrower is called a joint personal loan. Some lenders don’t permit cosigners on personal loans, but do allow co-borrowers. Make sure you understand which option a lender is offering before applying for a loan.
| Question | Cosigner | Co-borrower |
|---|---|---|
| Is this person responsible for repayment? | Yes (but only if the primary borrower can’t) | Yes |
| Can this person access or use the loan funds? | Generally no | Yes |
| Who is the loan intended for? | Primary borrower | Both applicants |
| Can this person help the application get approved? | Yes | Yes |
| What is the typical use case? | Primary borrower needs help qualifying | Both applicants will use the funds |
Note that exact rights and obligations depend on the lender and loan agreement.
When is a personal loan with a cosigner a good idea?
A cosigner or co-borrower may be useful to you in one of the following circumstances.
- You cannot qualify on your own: If your credit history is limited, you have a low score, you lack a stable income or you have a lot of debt, you could have a hard time qualifying for a personal loan on your own. A cosigner can help boost your chances. That said, think about ways to improve your profile, such as by strengthening your credit score and paying off debt.
- You want to compare whether adding another applicant improves your offers: Even if you think you can qualify on your own, it’s possible a cosigner could unlock better loan terms, lower interest rates or reduced fees, ultimately making it cheaper to borrow. Before you take out a loan, you should always compare multiple offers.
- You need a co-borrower for a shared expense: If you and someone else are taking out the loan for a joint expense, then it makes sense for both of you to have access to loan funds and equal responsibility for loan repayment, as is the case with joint loans. For instance, you and your spouse may want to take out a home improvement loan.
- You can afford the payment yourself: Make sure the loan is affordable, regardless of whether you have a cosigner. Even if your cosigner enables you to qualify for a higher loan amount, you should be sure not to borrow more than you can afford to pay back. Use the LendingTree personal loan calculator linked in the next section to see how much your monthly payments could be.
How much could a cosigner help you save?
You can prequalify for a personal loan with a cosigner to see how much you could save compared to the offers you receive when looking on your own. How much you’ll save will vary depending on the lender, the loan amount, the loan term, your financial situation and your cosigner’s financial situation.
The example below — which is illustrative only — can give you a sense of how much cheaper a lower APR can make your loan. You can use LendingTree’s personal loan calculator to better understand how your APR affects the cost of your loan.
Let’s say without a cosigner you qualify for a $5,000 loan with an APR of 27.29% (the average APR for fair credit borrowers on the LendingTree platform) and a payoff term of four years. Over those four years, you’ll pay $3,335.70 in interest.
If you add a cosigner, you may qualify for a lower rate. In this case, say you now qualify for a 17.87% APR on the same loan. You’ll now pay $2,036.21 in interest over the life of the loan, lowering the cost of borrowing by more than $1,000.
How to apply for a personal loan with a cosigner or co-borrower
If you use a cosigner or co-borrower, both you and the other person will fill out the application. You’ll need to:
- Decide whether you need a cosigner or co-borrower: Prequalify to see how much a personal loan may cost you without a cosigner or co-borrower. If you don’t think you’ll be able to afford the payments, the rates are too high or you don’t qualify, that may indicate that you need to find a cosigner or co-borrower.
- Review both applicants’ credit and finances: Does your potential cosigner or co-borrower have a better credit score than you, a more stable income and/or other financial strengths that could help you get a better loan? Do both you and the other person have the capacity to take on this debt? Weigh these questions before you apply.
- Find out whether lenders accept cosigners or co-borrowers: Decide whether you need a cosigner or a co-borrower for your personal loan. Some lenders only permit co-borrowers (for example, SoFi and Prosper).
- Prequalify and compare offers where available: Some lenders offer prequalification, which allows borrowers to get a sense of the type of loan they could get before they officially apply without impacting their credit. Although prequalification doesn’t guarantee approval, it can help you weigh options.
- Review the agreement and make a repayment plan: Your work isn’t done once you apply for the personal loan. Both you and your cosigner or co-borrower should carefully review the loan agreement before you sign on. You should also establish a clear repayment plan for the loan.
Risks of using a cosigner or co-borrower
When you use a cosigner or co-borrower, that person is making a commitment that lasts for the length of your loan. Associated credit impacts can outlive a loan’s repayment term. Make sure both of you understand the risks of the personal loan.
- Credit impact: When you and your cosigner or co-borrower apply for the loan, the lender will run a hard credit inquiry, which can have a small impact on your credit score. If the main borrower on a cosigned loan or one person with a joint loan misses a payment or causes the loan to default, both of your credit scores are at stake.
- Repayment responsibility: Cosigners are legally obligated to repay your loan if you can’t, while co-borrowers are legally responsible for the loan regardless of your ability to pay.
- Future borrowing capacity: A personal loan will affect your DTI ratio and that of your cosigner or co-borrower. A higher DTI ratio can make it more difficult to get approved for future loans with favorable terms.
- Relationship strain: If you miss payments that your cosigner or co-borrower expects you to make, this can damage your personal relationship with the cosigner or co-borrower. Outlining a repayment plan with your cosigner or co-borrower before you take out the loan can help you avoid this situation.
How to protect your credit and your cosigner’s credit
When you borrow with a cosigner, how you handle your loan payments will directly affect their credit — and your relationship. Here’s how to protect your cosigner:
-
Make sure you can afford the monthly payments.
Before you sign, estimate your monthly payments with a personal loan calculator, then use an app like YNAB or Monarch to see if the payment fits in your budget. Be honest with yourself — this isn’t the time to fudge numbers. -
Actively plan for on-time payments.
Late payments will hurt your cosigner’s credit. If you know you’ll have enough money in your bank account, sign up for automatic payments to ensure you’re not late. You can also set a monthly calendar reminder on your phone. -
Have an honest conversation.
Make sure your cosigner understands the risks that come with cosigning a loan, and talk openly about their expectations. What should happen if you suddenly can’t make payments? Are they comfortable spotting you for a month or two? How will you earn extra money to pay back the loan?
Talking about finances with your cosigner before you get a loan will open lines of communication and minimize the risk that you don’t understand each other. Consider writing out a simple contract to make sure your expectations are aligned.
Parents and cosigning
Parents appear hesitant to put their own finances on the line for their children, even as many remain open to the idea under the right circumstances.
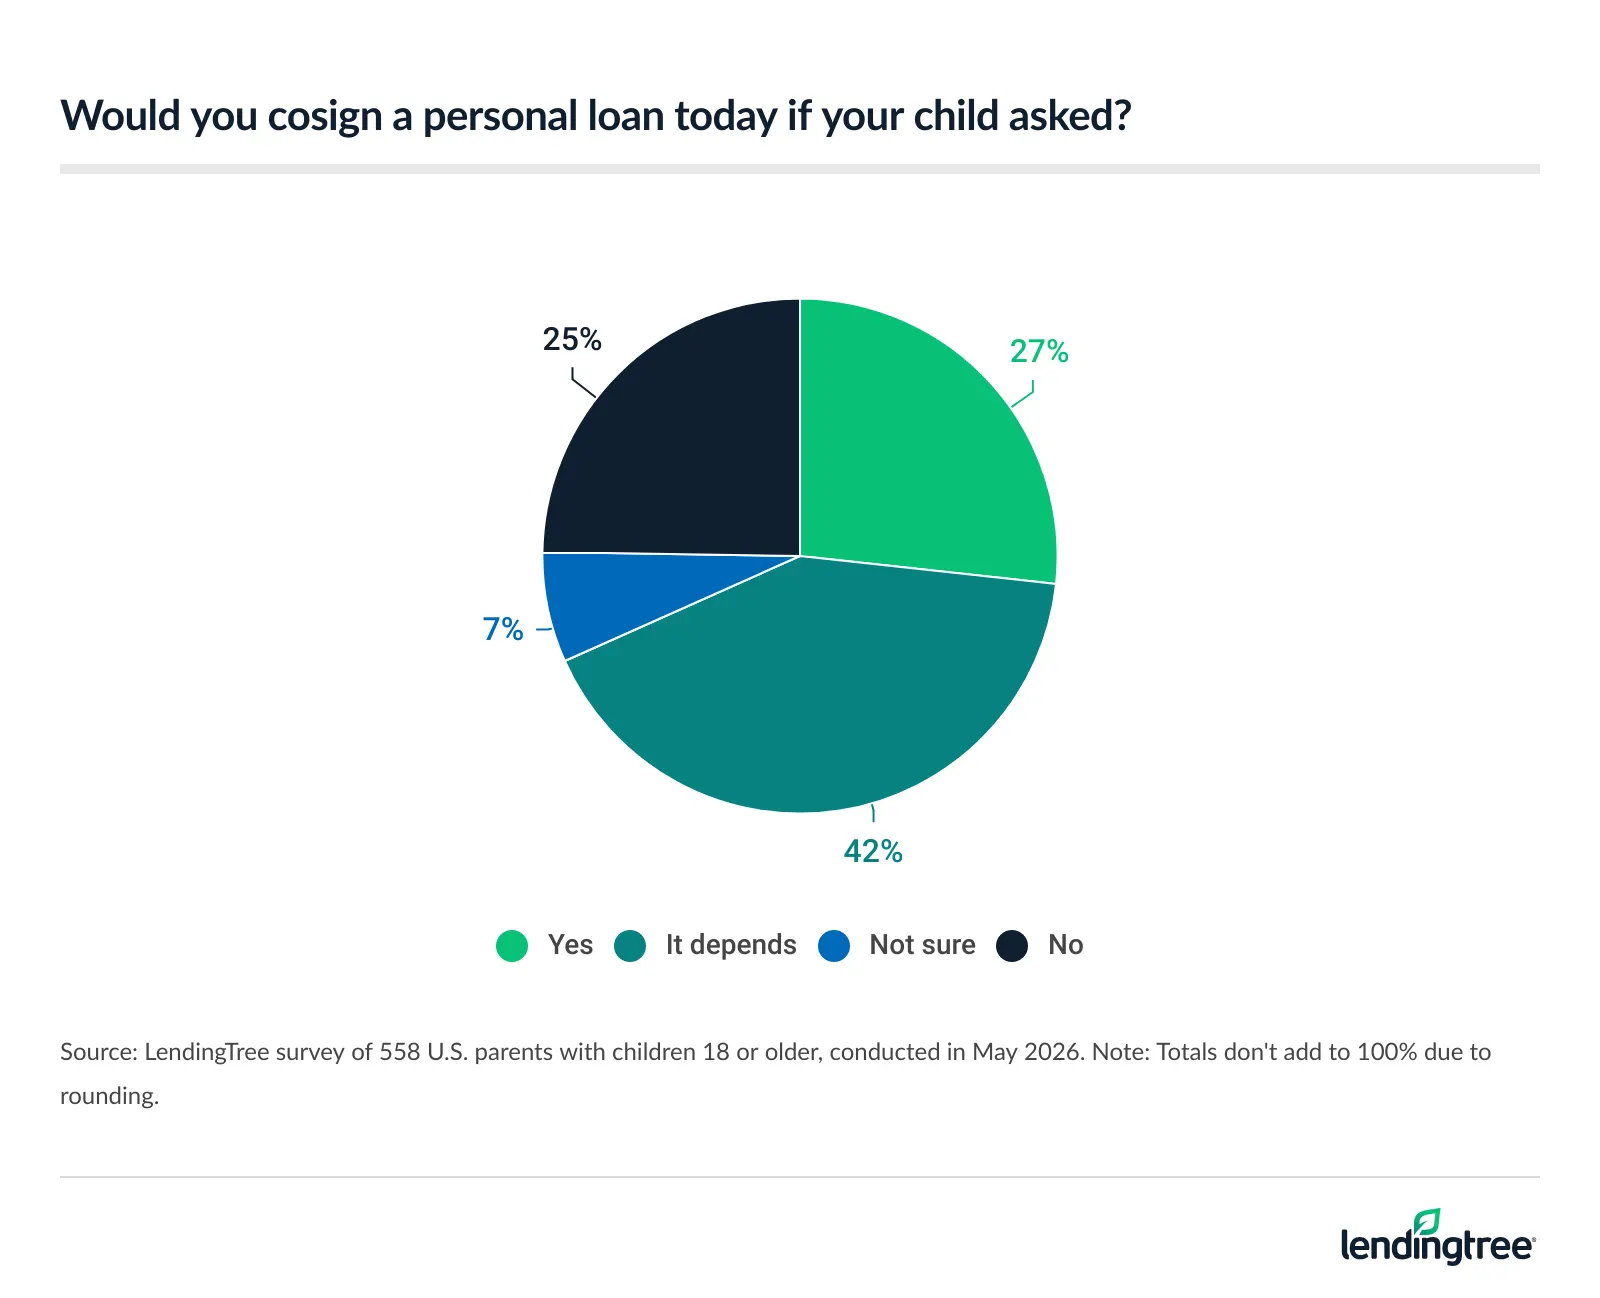
While only 23% of parents with children 18 or older say they’ve ever cosigned a personal loan for one of their kids, 21% who haven’t have at least considered it. Still, uncertainty dominates: 42% say whether they would cosign today depends, compared with 27% who say yes outright.
Among those unwilling to cosign today, the biggest concern is affordability, with 34% saying they can’t afford the risk. And for parents who’ve cosigned before, the experience hasn’t always been smooth — 20% say they made at least one payment on the loan themselves, while even more (23%) say the experience caused stress.
Key findings
-
Parents are far from universally comfortable cosigning for their children.
Just 27% of parents with kids 18 or older say they’d cosign a personal loan if asked today, while 25% say they wouldn’t and 42% say it depends. Among those unwilling to cosign, 34% say they can’t afford the risk. -
Only 23% of parents with children 18 or older say they’ve ever cosigned a personal loan for one of their kids.
Among those who have, the financial stakes were often significant — 40% say the last loan they cosigned was for $10,000 or more. The experience also came with downsides for some: 20% say they made at least one payment on the loan themselves, while 23% say it caused them stress.
Methodology
LendingTree commissioned QuestionPro to conduct an online survey of 558 U.S. parents with kids 18 or older from May 4 to 6, 2026. The survey of parents ages 18 to 80 was administered using a nonprobability-based sample, and quotas were used to ensure the sample base represented the overall population. Researchers reviewed all responses for quality control.
We defined generations as the following ages in 2026:
- Generation Z: 18 to 29
- Millennials: 30 to 45
- Generation X: 46 to 61
- Baby boomers: 62 to 80
Alternatives to a cosigner loan
If using a cosigner doesn’t appeal to you or isn’t a viable path, you may have other options. Keep in mind that each of the choices below comes with tradeoffs.
| If you… | Consider | Why it may help | Keep in mind |
|---|---|---|---|
| Want to see whether you can qualify alone | Prequalifying with multiple lenders | May show potential rates and terms before a formal application | Prequalification policies vary and do not guarantee approval |
| Have lower credit | A personal loan for bad credit | Some lenders have more flexible credit requirements | Rates and fees may be higher |
| Have an asset to pledge | A secured personal loan | Collateral may improve your approval odds | You could lose the collateral if you default |
| Need to share the loan funds with someone else | A joint loan with a co-borrower | Both applicants may qualify together and access the money | Both people are responsible for repayment |
How we chose the best personal loans with a cosigner
We reviewed more than 40 lenders and loan marketplaces to determine the best five personal loans with a cosigner or co-borrower. To make our list, lenders must offer cosigner or co-borrower loans with competitive annual percentage rates (APRs).
From there, we assessed each lender across four categories: eligibility and access; cost to borrow; loan terms and options; repayment support and tools.
According to our standardized rating system, the best cosigner loans come from First Tech Federal Credit Union, PenFed Credit Union, Prosper, SoFi and Upgrade.
Why trust LendingTree’s methodology?
Our writers and editors dig through the facts, contact lenders directly and even go through the application process ourselves if it helps better explain what you can expect. As a Certified Financial Education Instructor℠, I’m committed to breaking down complex financial details so people can make confident, informed decisions with their money.
Jessica’s experience in editing and financial education helps shape LendingTree articles that are clear, accurate and truly useful to readers. Her certification means our recommendations are built on a foundation of consumer-first financial knowledge — not just numbers.
Our categories
We assess how easy it is for people to qualify and apply. This includes state availability, soft-credit prequalification, membership requirements, funding speed and whether borrowers with less-than-excellent credit can get a loan.
We evaluate how affordable the loans are based on minimum and maximum APRs, loan fees and rate discounts. Lenders with unclear or potentially predatory costs receive lower scores.
We consider repayment term flexibility, loan amount ranges and whether options like secured loans, joint loans or direct-to-creditor payments are offered — plus whether the lender clearly communicates these options.
We evaluate borrower experience after funding: customer service access, hardship or forbearance programs, payment flexibility and digital tools like mobile apps or credit monitoring.
Our process
We gather data directly from lenders through their websites, disclosures and direct communication with company representatives. Our editorial team verifies and updates information regularly. We value transparency and award less favorable scores when lenders obscure or omit details.
Our editorial team applies the same scoring model and standards to every lender. Lenders cannot pay to influence our ratings. Read more about our editorial guidelines.
Frequently asked questions
A cosigner with a strong financial profile can boost your odds of approval. That said, adding a cosigner doesn’t guarantee that you’ll be approved by a lender.
Lenders have different requirements. Generally, a cosigner with good credit is one with a FICO Score of at least 670. Higher scores will typically help you access better loan rates and more favorable terms.
You could need a cosigner or co-borrower if:
- You have bad credit (a FICO Score below 580)
- You have little to no credit history
- Your income alone doesn’t meet a lender’s debt-to-income requirements
- You’ve been denied a personal loan and want to strengthen your application
You may not need a cosigner if you have a thin credit file but steady income or education history — lenders like Upstart evaluate applicants using income, employment and education data in addition to credit score.
In some instances, lenders may allow borrowers to remove their cosigners after they meet certain conditions, such as making a certain number of payments on time.
Check your intended lender’s policy before taking out a loan. You may need to refinance your personal loan if you want to remove the cosigner.
No, cosigners don’t get the loan money. Co-borrowers, however, do have access to loan funds. See our explanation on the difference between cosigners and co-borrowers.
If you can’t repay a loan with a cosigner, your cosigner is legally obligated to make payments instead. Any late payments from you can harm your credit score and your cosigner’s credit score.
If neither of you can afford payments, you can talk to the creditor about options and eventually consider debt relief options.