USAA Personal Loan Review


- APR (with autopay)
- Starting at 9.99%
- Amount
- $2.5k – $100k
- Term
- 12 to 84 months
- Origination fee
- None
- Min. credit score
- Not specified
- Eligibility and access: 1/5
- Cost to borrow: 2.5/5
- Loan terms and options: 4.2/5
- Repayment support and tools: 5/5
USAA Bank offers military members, veterans and their families with various financial products and services, including personal loans ranging from $2,500 to $100,000. Here’s what you need to know.
- Flexible loan terms: Borrowers can take out loans with repayment terms as short as 12 months or as long as 84 months; however, your repayment terms will depend on the amount you borrow and your creditworthiness.
- Large range of loan amounts: USAA members can borrow as little as $2,500 and up to $100,000. This loan range is much more flexible than what some other lenders offer.
- Only serves those with military ties: If you want to get a loan through USAA, you’ll need to be a member of the military, a veteran or a family member of someone in the military. You must become a member of USAA before you can get a personal loan.
- No application fees: USAA does not charge any application fees. USAA also does not charge prepayment penalties, so you can repay your personal loan without incurring extra fees.
- Autopay discount: USAA offers a discounted rate for signing up for automatic payments, which could save you 0.25% on your APR.
USAA pros and cons
While USAA isn’t perfect for everyone, it offers flexible personal loans to those who qualify.
Pros
- Offers a wide range of loan amounts and terms
- No fees for early repayment
- Typically offers quick loan decisions
Cons
- Only serves those with military ties
- Doesn’t offer prequalification
- Requires USAA membership
Aside from its flexible loan amounts ($2,500 to $100,000) and numerous repayment term options (12 to 84 months), USAA also offers quick loan decisions. In fact, the USAA site says most people get instant decisions when they apply, which can be a huge perk if you’re looking for a quick loan.
You need to become a USAA member to get a personal loan, and you must have a military tie to be approved for membership. USAA doesn’t allow you to prequalify, so you’ll have to submit to a hard credit check in order to see your rates.
Learn more about the best debt consolidation loans and lenders.
USAA requirements
While USAA does provide guidance on how to become a member, the lender doesn’t offer much insight into its personal loan requirements.
USAA does publish its membership eligibility requirements, though. USAA membership is available to:
- Active duty, guard or reserve military members
- Veterans
- Employees of certain federal agencies
- Cadets or midshipmen
- Officer or officer warrant candidates
- Spouses, widows, unremarried former spouses and children of USAA members
If you meet the basic membership requirements above, you may need to disclose how you plan to use your personal loan. While USAA does allow borrowers to use its funding for a variety of purposes, there are certain expenses you cannot put the money toward.
| USAA loans CAN be used for… | USAA loans CANNOT be used for… |
|---|---|
|
|
If USAA’s loan options won’t work for your borrowing needs, be sure to shop around for a lender that helps you meet your financial goals and can offer you the best-fitting rates, terms and amounts.
How to get a personal loan with USAA
In order to get a USAA personal loan, you’ll need to become a member first. Here’s what you need to know about the process:
Become a USAA member
If you’re not already a USAA member, you’ll need to apply to become one before you can get a personal loan.
During this process, in addition to your contact information, you’ll need to report your experience in the U.S. Armed Forces, your military status, branch, rank and when you served.
Fill out an application
Once you’re approved to join USAA, you can apply for a personal loan.
USAA doesn’t offer soft credit inquiries to those applying for a loan, meaning you’ll have an impact on your credit score if you want to check your rates with USAA.
So, if you want to see whether you qualify, you’ll have to submit to a hard credit inquiry, which typically causes your credit score to drop by a few points. Because of this, you may want to check if you prequalify for a loan with any other lenders before applying with USAA.
Once you access your potential rates, terms and amounts you’re eligible for, you’ll need to choose what loan you want to go with.
During this process, you may also need to verify your personal information such as your income and identity through documentation such as pay stubs, W-2s and a government-issued ID.
Sign your contract
If you’re approved for a personal loan, you’ll need to sign your loan agreement and close on your loan. After you’ve completed this part of the process, USAA will send your funds to your USAA Bank account.
If you’re not approved, you may want to consider tactics to increase your chances of qualifying for a loan. This can include raising your credit score by cutting down on your debt and paying your bills on time as well as checking your credit report for any errors.
How USAA compares to other personal loan companies
Even if you believe USAA aligns with what you’re looking for in a personal loan, it never hurts to shop around and compare other lenders. Here’s how USAA stacks up against similar personal loan lenders.
| Lender | USAA Bank | Navy Federal Credit Union | SoFi |
|---|---|---|---|
| LendingTree’s rating | 3/5 | 4.1/5 | 4.9/5 |
| Minimum credit score | Not specified | Not specified | 600 |
| APRs | Starting at 9.99% (with autopay) | 8.74% – 18.00% | 6.99% – 35.49% (with discounts) Terms and conditions apply. SOFI RESERVES THE RIGHT TO MODIFY OR DISCONTINUE PRODUCTS AND BENEFITS AT ANY TIME WITHOUT NOTICE. To qualify, a borrower must be a U.S. citizen or other eligible status, be residing in the U.S., and meet SoFi’s underwriting requirements. Not all borrowers receive the lowest rate. Lowest rates reserved for the most creditworthy borrowers. If approved, your actual rate will be within the range of rates at the time of application and will depend on a variety of factors, including term of loan, evaluation of your creditworthiness, income, and other factors. If SoFi is unable to offer you a loan but matches you for a loan with a participating bank, then your rate may be outside the range of rates listed above. Rates and Terms are subject to change at any time without notice. SoFi Personal Loans can be used for any lawful personal, family, or household purposes and may not be used for post-secondary education expenses. Minimum loan amount is $5,000. The average of SoFi Personal Loans funded in 2025 was around $32K. Based on loans funded from 1/1/2025-12/31/2025. Information current as of 10/02/26. SoFi Personal Loans originated by SoFi Bank, N.A. Member FDIC. NMLS #696891 (www.nmlsconsumeraccess.org). See SoFi.com/legal for state-specific license details. See SoFi.com/eligibility for details and state restrictions. Fixed rates from 6.99% APR to 35.49% APR. APR reflect the 0.25% autopay interest rate discount and a 0.25% member rate discount. SoFi Platform personal loans are made either by SoFi Bank, N.A. or , Cross River Bank, a New Jersey State Chartered Commercial Bank, operating from its Delaware branch, Member FDIC, Equal Housing Lender. SoFi may receive compensation if you take out a loan originated by Cross River Bank. These rate ranges are current as of 09/14/26 and are subject to change without notice. Not all rates and amounts available in all states. See SoFi Personal Loan eligibility details at https://www.sofi.com/eligibilitycriteria/#eligibility-personal. Not all applicants qualify for the lowest rate. Lowest rates reserved for the most creditworthy borrowers. Your actual rate will be within the range of rates listed above and will depend on a variety of factors, including evaluation of your credit worthiness, income, and other factors. Loan amounts range from $5,000– $100,000. The APR is the cost of credit as a yearly rate and reflects both your interest rate and an origination fee of 9.99% of your loan amount for Cross River Bank originated loans which will be deducted from any loan proceeds you receive and for SoFi Bank originated loans have an origination fee of 0%-7%, will be deducted from any loan proceeds you receive. Autopay Discount: The SoFi 0.25% autopay interest rate reduction requires you to make monthly payments using SoFi’s automatic monthly deduction from a savings or checking account. The discount will discontinue and be lost when you do not have autopay enabled. You’re not required to set up autopay to obtain this loan. Member Rate Discount: To be eligible for an additional 0.25% interest rate reduction on a Personal Loan, you must, within 31 days of loan funding, either (1) meet SoFi Plus eligibility criteria, (2) receive an Eligible Direct Deposit into a SoFi Checking or Savings account, or (3) receive at least $5,000 in Qualifying Deposits into a SoFi Checking or Savings account. You must continue to meet at least one of the above eligibility criteria every 31 days to maintain the discount. See the SoFi Plus terms for details on SoFi Plus subscription. For more details on Eligible Direct Deposit or Qualifying Deposits, please see https://www.sofi.com/legal/banking-rate-sheet. Once you become eligible during the initial period, the discount will be removed or reinstated depending on whether the criteria have been met. Each time your loan is re-amortized, your monthly payment amount will change based upon the interest rate that was in place. SoFi reserves the right to modify or terminate this offer at any time for unenrolled participants. You are not required to meet these criteria to be approved for a loan.[/generic-modal] |
| Loan amounts | $2,500 – $100,000 | $250 to $150,000 | $5,000 – $100,000 |
| Repayment terms | 12 to 84 months | Up to 60 months | 24 to 84 months |
| Origination fee | None | None | 0.00% – 7.00% (optional) |
| Funding timeline | Not specified | As soon as the same day | Get money as soon as the same business day |
| Bottom line | USAA Bank stands out for offering a wide range of loan amounts and terms, and it’s great for smaller or shorter loans. But SoFi and Navy Federal Credit Union offer lower starting rates and are more transparent about their funding timeline. | Similar to USAA Bank, Navy Federal Credit Union is a lender for those with military affiliations. This lender offers both small and large loan amounts with APRs capped at 18.00%. | SoFi has lower starting rates and is more transparent about its eligibility requirements. Unlike USAA Bank, it also allows consumers to prequalify. |
How we rated USAA
We evaluate personal loan lenders on more than just interest rates. Our goal is to show how accessible, affordable, transparent and supportive each lender really is.
Our categories
Every lender is scored out of 5 stars, with 5 stars being the highest rating. LendingTree loan experts determine this score using dozens of underlying data points across four weighted categories covering the full borrowing journey.
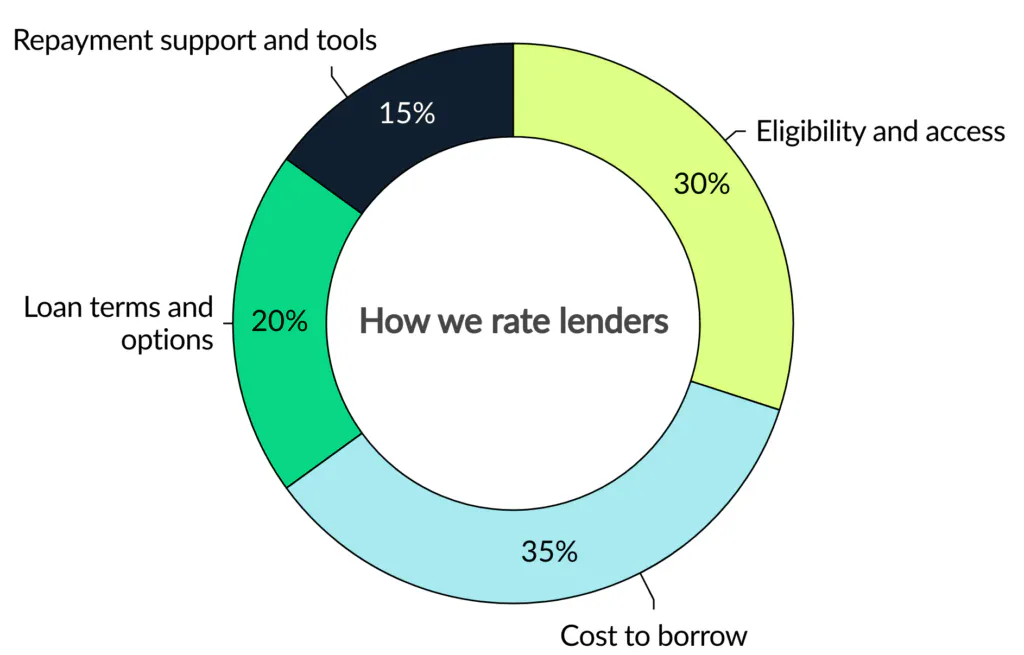
We assess how easy it is for people to qualify and apply. This includes state availability, soft-credit prequalification, membership requirements, funding speed and whether borrowers with less-than-excellent credit can get a loan.
We evaluate how affordable the loans are based on minimum and maximum APRs, loan fees and rate discounts. Lenders with unclear or potentially predatory costs receive lower scores.
We consider repayment term flexibility, loan amount ranges and whether options like secured loans, joint loans or direct-to-creditor payments are offered — plus whether the lender clearly communicates these options.
We evaluate borrower experience after funding: customer service access, hardship or forbearance programs, payment flexibility and digital tools like mobile apps or credit monitoring.
Our process
We gather data directly from lenders through their websites, disclosures and direct communication with company representatives. Our editorial team verifies and updates information regularly. We value transparency and award less favorable scores when lenders obscure or omit details.
In some cases, our editors may apply a small adjustment (no more than 4% of the overall score) to account for factors not captured by the methodology. This could include J.D. Power customer satisfaction surveys, recent regulatory actions or features that stand out in ways our rubric doesn’t measure directly.
Our editorial team applies the same scoring model and standards to every lender. Lenders cannot pay to influence our ratings.
Frequently asked questions
The only people who can access a USAA personal loan are:
- Active duty, guard or reserve military members
- Veterans
- Cadets or midshipmen
- Officer or officer warrant candidates
- Spouses, widows, unremarried former spouses and children of USAA members
While reputable lenders all perform hard credit pulls at some point during the personal loan application process, many lenders allow you to check if you prequalify for a personal loan beforehand without any impact to your credit score.
USAA, however, doesn’t allow you to prequalify for a loan. If you want to see your potential rates and terms, you’ll have to submit to a hard credit check.
If you’re not a current or former member of the military (or a family member of someone who is) you won’t be able to get a personal loan from USAA. If you don’t fit this criteria, you’ll need to find another personal loan lender.
Get personal loan offers from up to 5 lenders in minutes