More Than Half of Insured Drivers Say Auto Insurance Is a Financial Burden as 78% Cut Spending Amid Rising Premiums


Car insurance is a must-have for drivers, but it’s become one of the hardest bills to afford for many households.
This LendingTree survey of 2,000 U.S. consumers shows how far the strain reaches — leading drivers to cut spending, trim coverage, skip claims and, in some cases, go without insurance.
- Auto insurance is straining household budgets for a majority of insured drivers. More than half of auto insurance policyholders (55%) say coverage is a financial burden, including 24% who describe it as a large burden. Still, 69% say their coverage is worth the cost, while 31% disagree.
- Rising premiums are making people cut back on everyday spending. Nearly 4 in 5 insured drivers (78%) have cut back on at least one expense in the past year because of rising auto insurance premiums. Dining out (45%), entertainment (38%), groceries (35%) and clothing (31%) are the most common areas they’ve trimmed. Additionally, 25% of insured drivers have cut back on savings, while 13% have cut back on debt payments and 12% on retirement contributions.
- Drivers are trading protection for lower premiums, sometimes with regret. About 3 in 5 (61%) insured drivers are comfortable taking on higher out-of-pocket costs in exchange for lower monthly payments. Among drivers with liability-only coverage, 34% say they switched from full coverage in the past 12 months to save money. Overall, 24% of insured drivers say they’ve downgraded coverage and later regretted it.
- Affordability is pushing some drivers into coverage gaps. 3 in 10 insured drivers say they’ve driven without coverage. Among those drivers, 87% say they did so because they couldn’t afford auto insurance. Despite these affordability pressures, 45% of insured drivers primarily view insurance as a necessary safeguard, while 16% view it primarily as a source of peace of mind.
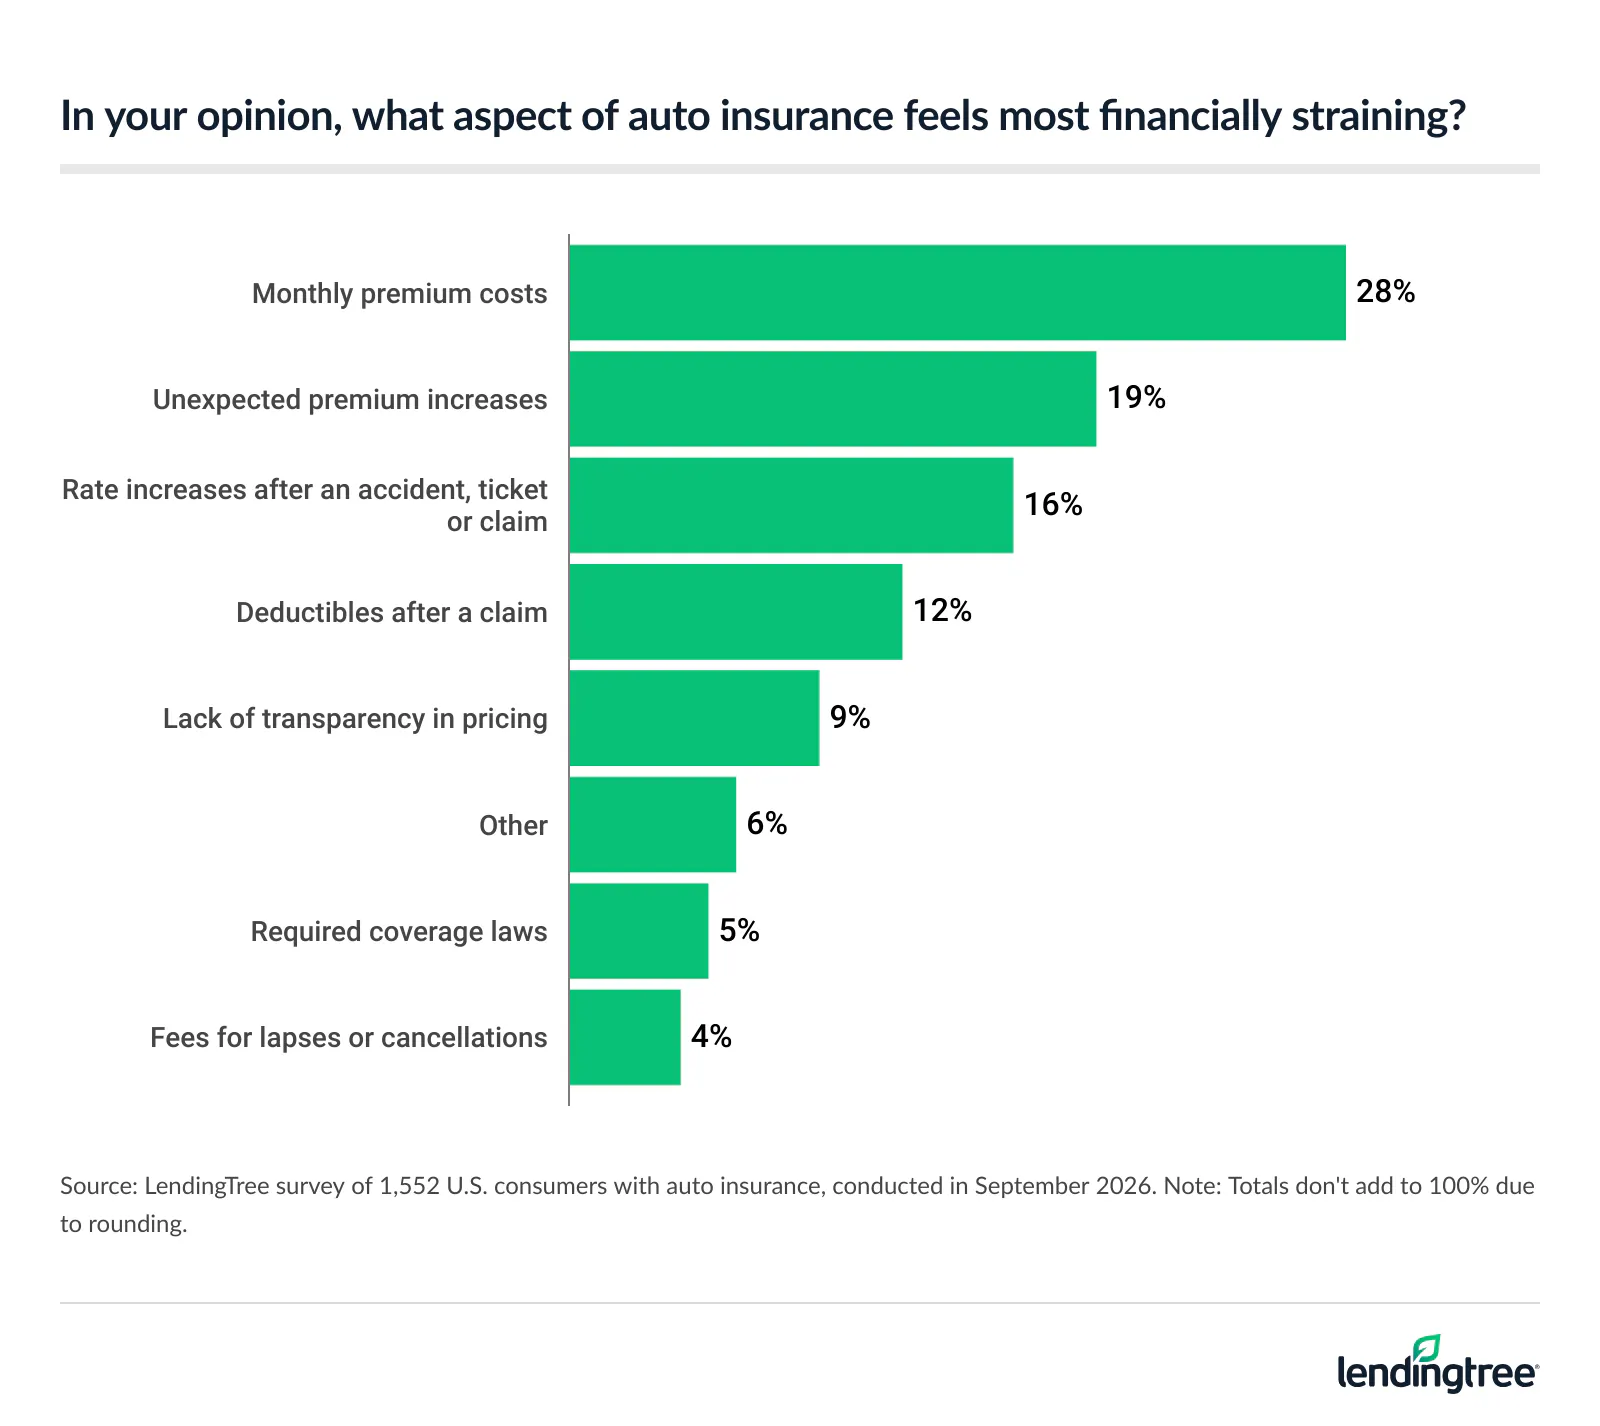
- Premium concerns are changing driver behavior beyond coverage decisions. More than one-third of insured drivers (35%) have avoided filing a claim because they feared their premiums would rise. When asked about the biggest financial strain related to auto insurance, 28% cite monthly premiums, followed by 19% who cite unexpected premium increases and 16% who cite rate increases after an accident, ticket or claim.
Most insured drivers feel the pinch but still see the value
More than half of insured drivers (55%) say their auto insurance is a financial burden, including 24% who describe that burden as large. Younger drivers and parents feel it most, with 77% of Gen Z drivers ages 18 to 29 and 73% of parents with children younger than 18 calling their coverage a burden.
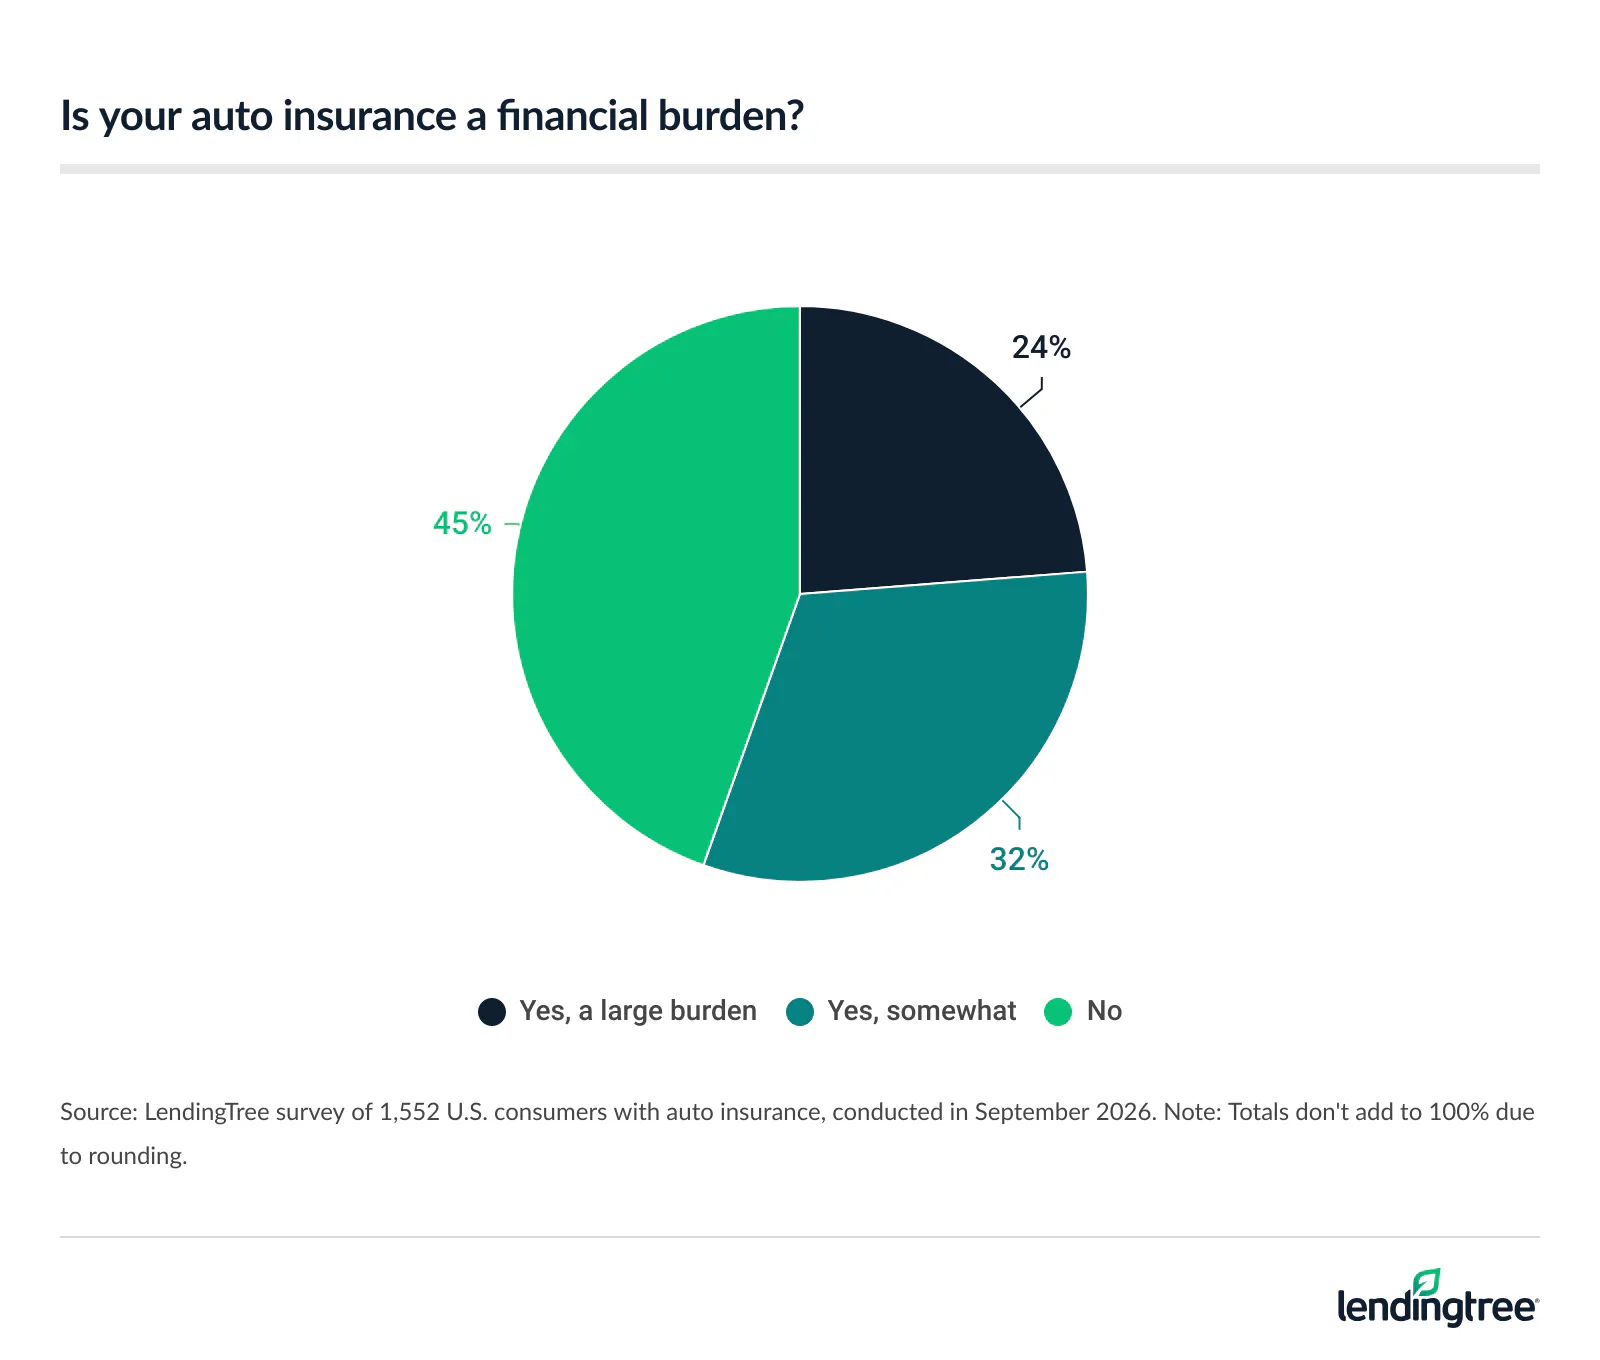
Yet 69% say their policy is worth the price, while 31% don’t. Those with more wiggle room are more likely to believe insurance is worth it, at 80% among six-figure earners compared with 64% among those earning less than $30,000.
Rob Bhatt, LendingTree car insurance expert and licensed insurance agent, says most people have been feeling the burden for several years.
“We’re still feeling the impacts from trends that emerged at the end of the COVID-19 pandemic,” he says. “This was when an increase in traffic accidents coincided with a spike in inflation. Insurance companies saw an increase in claims at a time when the costs of repairing or replacing cars had grown faster than normal. They raised their rates to keep up with their growing claims expenses.”
The effects showed up in household budgets. “Nationwide, we saw insurance rates rise by more than 30% between 2023 and 2025,” Bhatt says. “When car insurance rates rise quicker than your income, it takes up a larger share of your household budget. This is where the burden comes from for many people. The good news is that car insurance rates have stabilized a bit in 2026. However, as we’ve seen in the recent past, circumstances can change quickly.”
Higher premiums are squeezing everyday spending
Almost 4 in 5 insured drivers (78%) have cut back on at least one expense in the past 12 months because their premiums went up. Dining out is the most common casualty (45%), followed by entertainment (38%), groceries (35%) and clothing (31%).
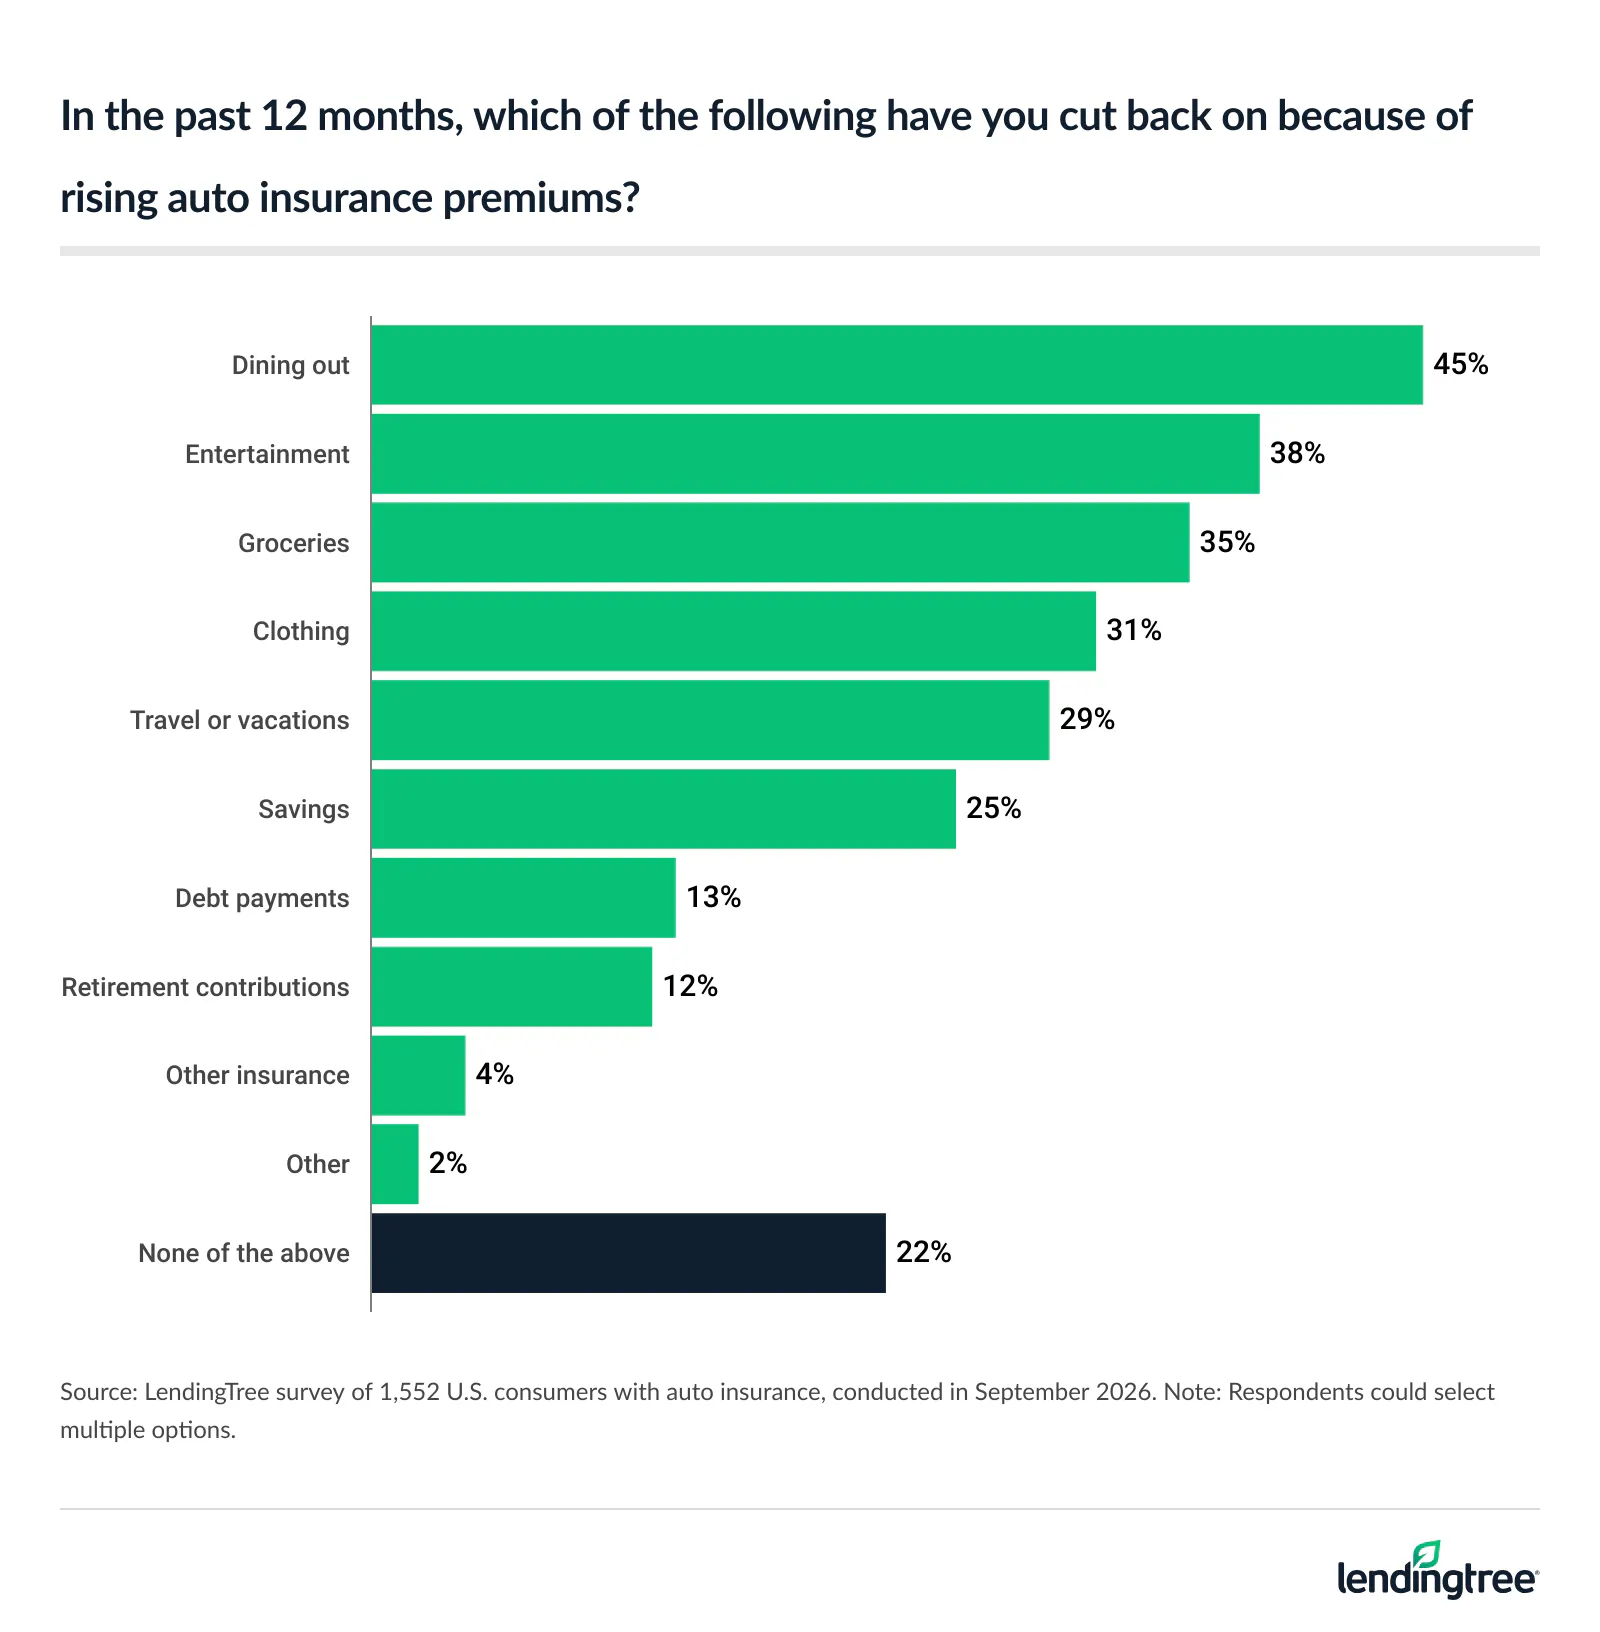
Some drivers are also cutting back on their financial futures. A quarter (25%) have reduced savings, 13% have cut debt payments and 12% have lowered retirement contributions.
Bhatt acknowledges that affording insurance can be difficult, but maintaining coverage is crucial.
“Shopping around for a cheaper rate and raising your deductible are good first steps for reducing your car insurance rate,” he says. “It’s also important to remember that other drivers may let their policies lapse. This makes it worth adding uninsured motorist coverage to your policy, if you don’t already have it.”
Notably, 22% of Americans say they don’t currently have auto insurance coverage.
Drivers are trading protection for lower payments, and some regret it
Many drivers are willing to take on more risk to save money each month. About 3 in 5 (61%) insured drivers say they’d accept higher out-of-pocket costs in exchange for a lower premium. Gen Zers are even more open to the trade, with 87% willing to do so.
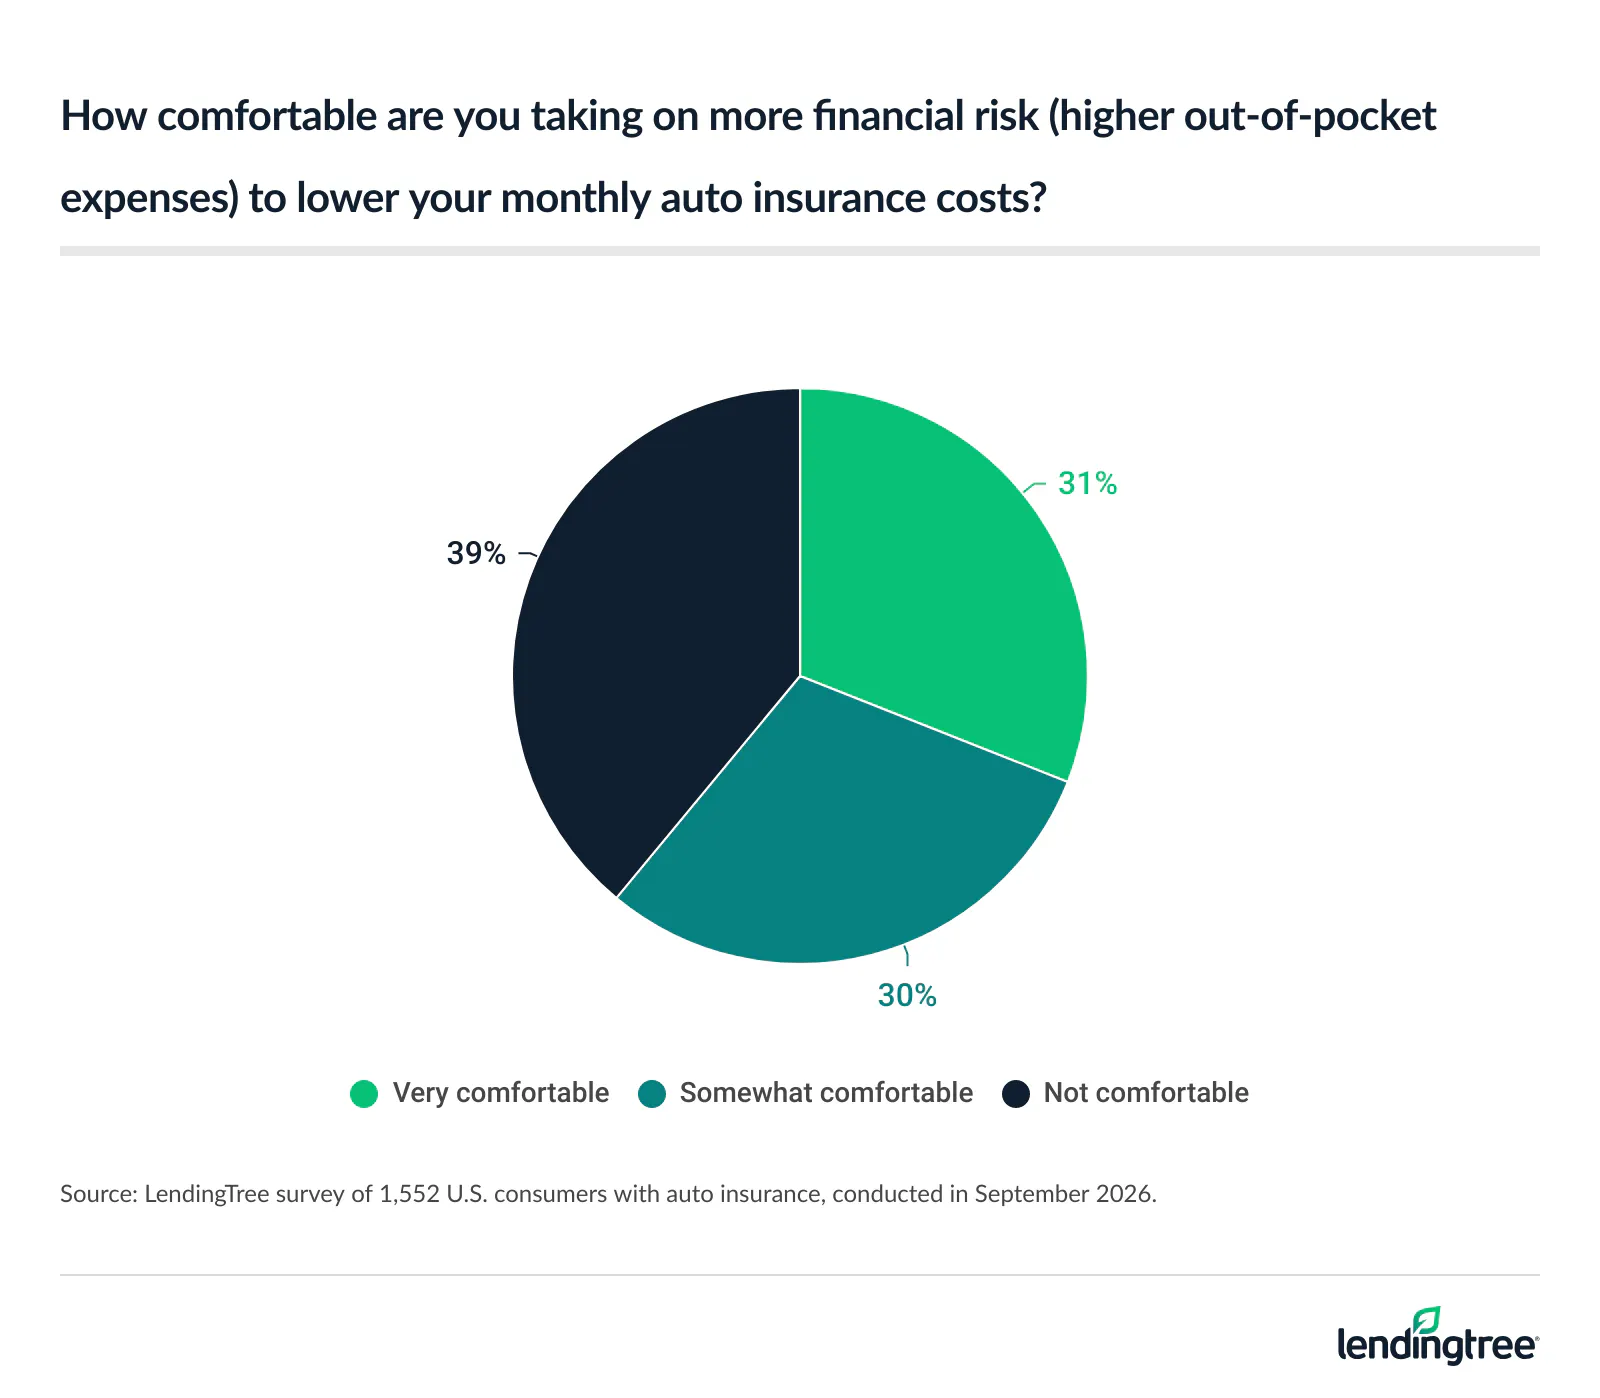
Some have already made the switch. Among drivers who now carry only liability coverage, 34% say they dropped full coverage in the past year to save money, compared with 51% among parents with children younger than 18. Overall, 24% of insured drivers say they downgraded their coverage and later regretted it.
Bhatt says dropping collision and comprehensive coverage can make sense in some cases. “If your car is worth less than a few thousand dollars, the benefits of collision and comprehensive may not be worth the price. If you make the change, make sure to set aside some or all of the money you save on car insurance in a savings account. If you never get into a car accident, you can use these funds to help pay for your next car.”
Where to draw the line is personal. “The exact value at which to drop full coverage depends on your financial situation and your comfort level with risk,” Bhatt says. “Some people have the financial resources to replace a $5,000 car on their own without blinking an eye. Others may face financial hardship from having to come up with $3,000 to replace their car after an accident. The benefits of full coverage diminish once your car’s value drops below this amount.”
Affordability is pushing drivers into risky coverage gaps
Thirty percent of insured drivers say they’ve driven without coverage, with parents with children younger than 18 (49%) and Gen Z drivers (48%) especially likely to have done so.
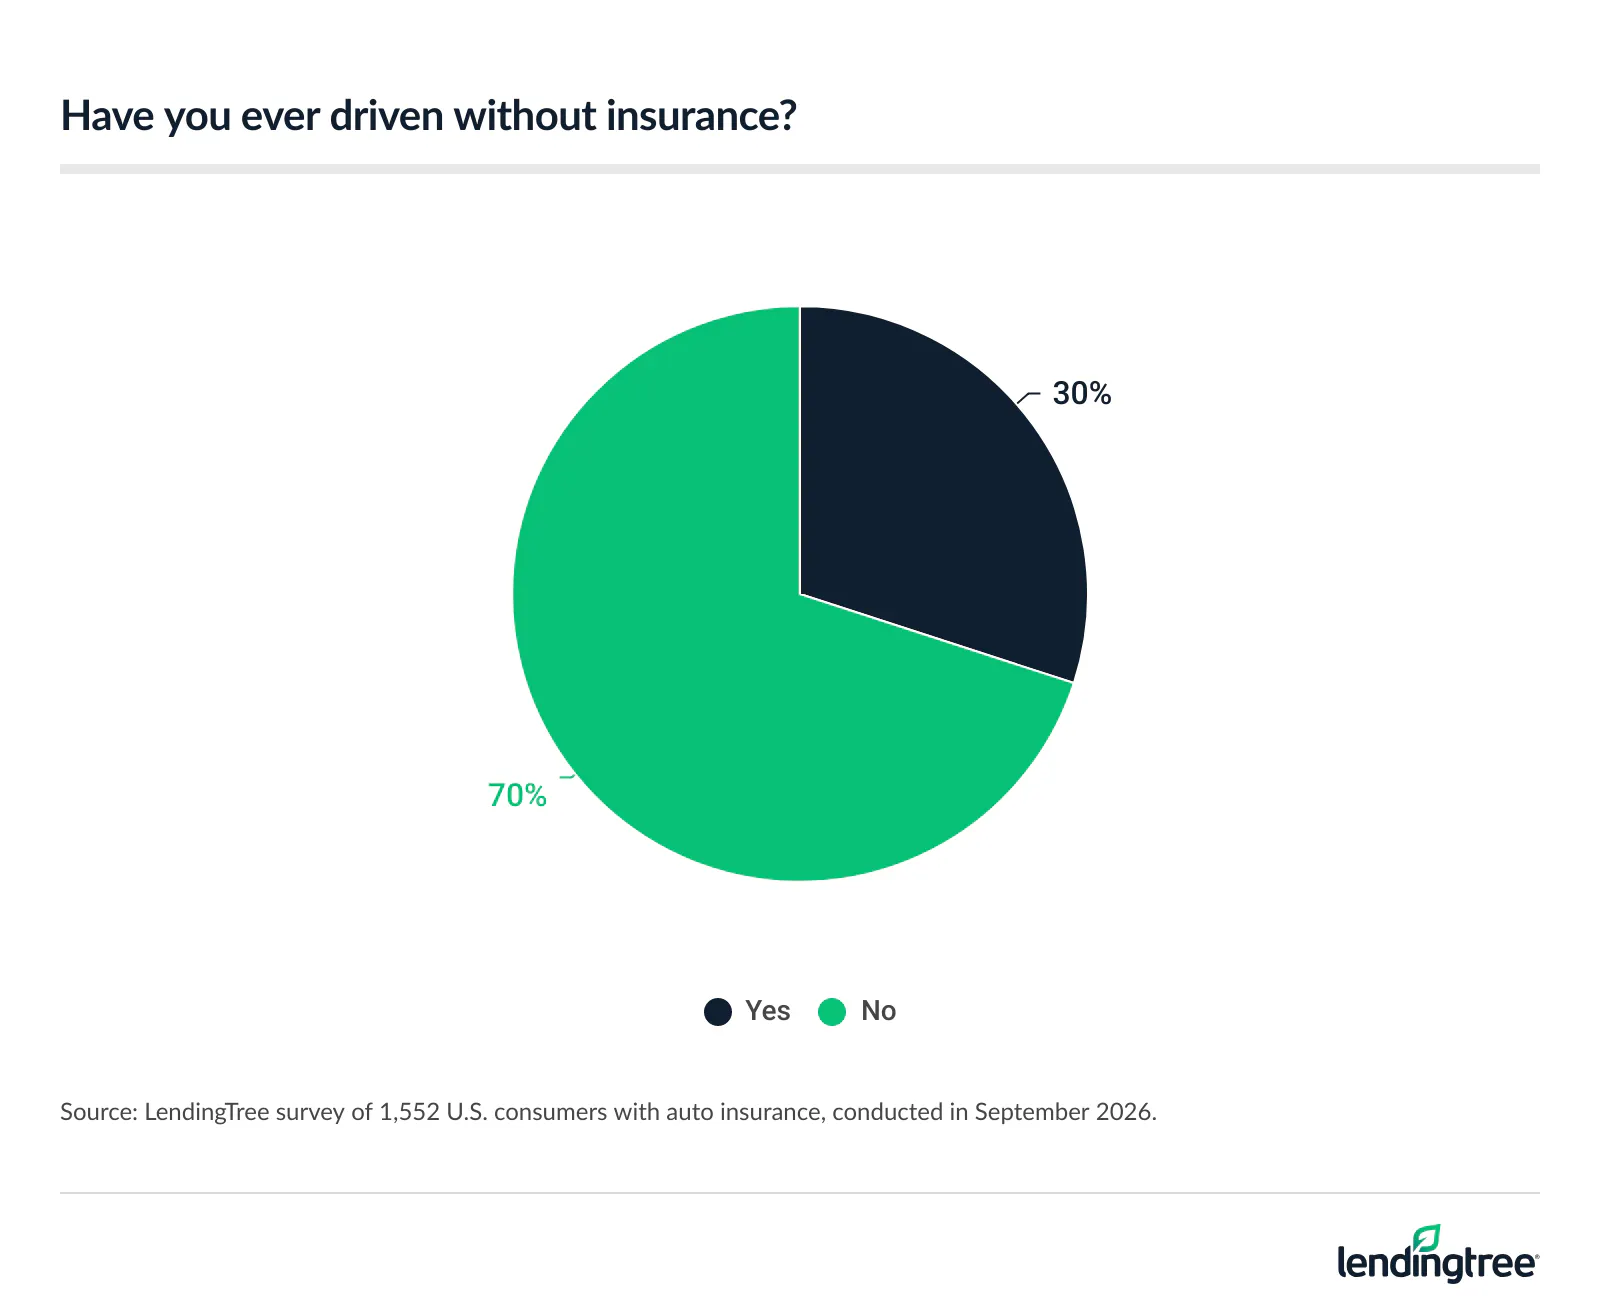
Across all drivers who’ve gone without insurance, 87% say they did so because they couldn’t afford coverage.
Most drivers don’t see insurance as optional. Only 10% of insured drivers say they’d carry it only if the law required it. Still, just 45% mainly see it as a necessary safeguard, while 16% see it primarily as a source of peace of mind.
Bhatt says even a short lapse can be costly. “The financial consequences can be substantial. If you cause an accident without insurance, you’re personally responsible for an accident victim’s medical bills and car repairs. These costs can devastate your finances. Car insurance usually also costs more after a lapse in coverage. Insurance companies see you as riskier to insure if you haven’t been continuously insured when you request a quote.”
The legal fallout can add to the cost. “In most states, getting caught driving without insurance can lead to a suspension of your driver’s license or vehicle registration,” Bhatt says. “The penalties also include fines and reinstatement fees. Most insurance companies also charge higher rates to drivers with prior insurance violations. As expensive as car insurance can be, going without insurance can often cost you more in the long run.”
Fear of higher rates is changing how drivers use their insurance
Premium worries go beyond coverage decisions. More than a third of insured drivers (35%) have avoided filing a claim because they were afraid their rates would go up. That share is higher among parents with children younger than 18 (55%) and Gen Z drivers (54%).
When asked what strains them most about auto insurance, 28% of drivers point to monthly premiums. Another 19% cite unexpected rate hikes, and 16% cite increases after an accident, ticket or claim.
Bhatt says skipping a claim should be the exception.
“It’s best to stick with insurance for any accident involving injuries or major damage to anyone’s vehicle,” he says. “This is what you pay for with insurance. Your rates may go up for a few years afterward, but major claims can get costly and complicated. A small fender-bender with another driver is trickier, but skipping a claim is worth considering only if the damage is minor and the other driver is cooperative. Even if the other driver is at fault, an insurance claim from any accident usually goes on your vehicle’s history report. This can reduce your car’s future resale value.”
Lowering your car insurance costs without sacrificing coverage: Top expert tips
Saving on auto insurance doesn’t necessarily mean cutting important protection. Consider these expert tips:
- Consider a higher deductible. “Raising your deductible can lower your insurance premium,” Bhatt says. “Just make sure you have enough money set aside to comfortably cover the higher out-of-pocket cost if you need to file a claim.”
- Shop around regularly. “Every insurer calculates rates differently, so another company may offer the same coverage for significantly less,” he says. “Compare quotes periodically, especially if your credit has improved or a violation has fallen off your driving record.”
- Reconsider full coverage on an older car. “If your vehicle has a low resale value, dropping collision and comprehensive coverage could significantly reduce your premium,” he says. “Before doing so, make sure you can afford to repair or replace the vehicle yourself.”
- Review your policy and discounts. “Check in with your insurance agent every year or two to see whether you qualify for new discounts or are paying for coverage you no longer need,” he says. “For example, you may be able to drop gap insurance after paying down enough of your auto loan.”
- Consider a safe-driving program. “If you’re a safe driver, ask about your insurer’s telematics or usage-based insurance program,” he says. “These programs typically monitor driving habits through an app or other device and may reward safer driving with a discount.”
Methodology
LendingTree commissioned QuestionPro to conduct an online survey of 2,000 U.S. consumers from Sept. 2 to 7, 2026. The survey was administered using a nonprobability-based sample, and quotas were used to help ensure the sample reflected the overall population. Researchers reviewed all responses for quality control.
Generations were defined as the following age groups in 2026:
- Generation Z: 18 to 29
- Millennials: 30 to 45
- Generation X: 46 to 61
- Baby boomers: 62 to 80