Auto Loan Calculator
Use the LendingTree car loan calculator to estimate your monthly car payment, total interest and total loan cost — just enter your loan amount, interest rate and loan term to see your results instantly and compare offers to save.


Advertising Disclosures
Loading Disclosures…
How Your Auto Loan Breaks Down
- Loan Amount:
- $26,064
- Sales Tax Paid:
- $2,064
- Total Payments:
- 48
Your monthly payment will be
$571.17/mo.
- Net Purchase Price
- $24,000.00
- Title & Registration Fees
- $0.00
- Total Interest
- $1,352.03
- Total Sales Tax
- $2,064.00
Understanding your auto loan calculator results
Your auto loan calculator results can help you estimate more than just your monthly payment. They can also show how much you may pay in interest, how much you’re financing and how changes to your loan amount, APR or term could affect the total cost of your car loan.
| Result | What it means | Why it matters |
|---|---|---|
| Monthly payment | The estimated amount you’ll pay each month based on your loan amount, interest rate and repayment term. | This helps you decide whether the loan fits your monthly budget. |
| Amount financed | The portion of the vehicle cost you’ll borrow after factoring in your down payment, trade-in value and any financed taxes or fees. | A lower amount financed usually means a lower monthly payment and less interest paid over time. |
| Total interest | The estimated amount you’ll pay to borrow money over the life of the loan. | This shows the true cost of financing beyond the vehicle price. |
| Total loan cost | The estimated full cost of the loan, including the amount borrowed and interest charges. | This helps you compare loan offers with different rates and terms. |
| Taxes and fees | Estimated added costs such as sales tax, title and registration fees, if entered into the calculator. Dealer fees and optional add-ons may also affect your final loan amount. | These costs can raise your amount financed and monthly payment. |
If your estimated monthly payment is higher than expected, try adjusting one variable at a time. A larger down payment, lower APR or less expensive vehicle can reduce your payment. A longer loan term can also lower your monthly payment, but it may increase the total interest you pay.
Don’t focus only on the monthly payment. A longer loan term may make your payment more affordable, but it can also increase your total borrowing cost. Compare the monthly payment and total interest before choosing a loan term.
How to use the LendingTree car loan calculator
-
Enter your numbers
Add your vehicle price, down payment, trade-in value, estimated APR and loan term. -
Review your estimated payment
Look at your monthly payment, amount financed and total interest. These numbers can help you decide whether the loan fits your budget. -
Adjust the numbers to compare options
Try a different loan term, APR, down payment or vehicle price to see how each change affects your monthly payment and total loan cost.
What affects your auto loan payment?
Several factors can change your estimated monthly car payment, including how much you borrow, your APR, loan term, down payment, trade-in value and whether you roll taxes or fees into the loan. Adjust one number at a time in the calculator to see how each factor affects your payment and total interest.
Loan amount
This is how much you borrow after making a down payment or applying trade-in value. If your car costs $40,000 and you put $5,000 down, your loan amount is $35,000 before taxes, fees or add-ons. Borrowing less usually means a lower monthly payment and less interest over time.
Average loan amount: $29,418 for new cars, $30,178 for used
Interest rate
Your APR is the cost of borrowing money, including interest and certain fees. A lower APR can reduce your monthly payment and the total interest you pay over the life of the loan. Use the table below to estimate your interest rate.
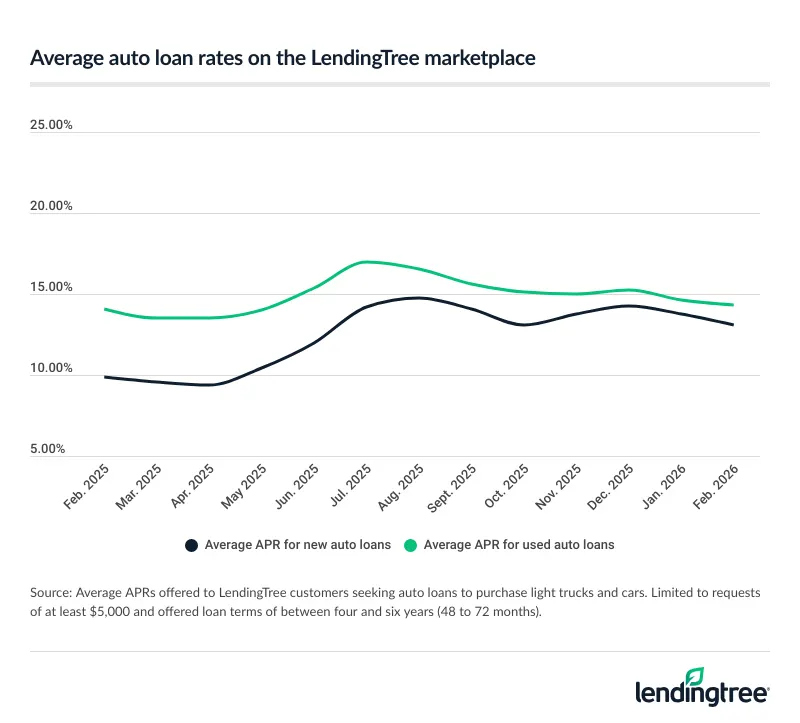
Average car loan rates: 11.44% new, 14.76% used
Loan term
This is how long you have to pay back your car loan. Save money on interest by choosing the shortest loan term with monthly payments you can afford.
Average loan term: 62 months
Down payment and trade-in value
A larger down payment or higher trade-in value reduces the amount you need to borrow. That can lower your monthly payment and may reduce the total interest you pay over the life of the loan.
Putting more money down can also help you avoid owing more than the car is worth, especially if you choose a longer loan term.
Taxes, title and registration fees can raise your total loan amount and monthly payment. Enter your estimated sales tax and title or registration fees in the calculator for a more accurate payment estimate. Dealer fees and optional add-ons may also increase your cost, so review the final numbers before you sign.
What to know about car loans
Car loans help you spread out the cost of your car over time. The two factors that matter most are your car loan rate and loan term — together, they determine how much you’ll pay.
Here’s how to save:
- Get a lower rate. Improve your credit and shop around for a car loan to get the best offer.
- Pick the right term. Choose the shortest term that fits in your budget. Shorter loans come with higher monthly payments, but you’ll pay less money in interest.
Car loan rates in 2026: Is now the right time to finance your vehicle?
Car loan rates rose over the summer, but the latest LendingTree data shows that used auto rates are starting to plateau while new auto loan rates continue to be a bit of a rollercoaster.
If you’re looking for a used car now, take advantage of this pause in rate hikes. But if you can afford to wait, see if the Fed continues to cut rates — this might eventually mean lower rates for your car loan and more savings in your pocket.
How your credit score affects your car payment
It’s hard to know if you’re getting a good deal on your car loan, so we’ve made it easy. Compare the rates in your offers to the average rate for your credit band in the table below.
| Credit score range | Average new car APR | Average used car APR |
|---|---|---|
| Excellent (800 and above) | 7.40% | 8.03% |
| Very good (740-799) | 7.40% | 7.81% |
| Good (670-739) | 8.52% | 10.57% |
| Fair (580-669) | 18.37% | 21.72% |
| Poor (Under 580) | 21.54% | 24.06% |
But the best way to know if you’re getting a good deal is to compare quotes from different lenders before choosing one. You can save $2,346 on average by shopping for your car loan with LendingTree and choosing your best offer.
How much can you afford to borrow?
Buying a car is exciting, but it’s also a big financial decision. We’ll walk you through how to calculate what you can afford before you fall in love with a particular car that could stretch your budget too far.
1. Check your budget. Subtract your monthly expenses from your income to see how much car payment you can afford, and leave a cushion to avoid stretching your budget too far. You can use a personal finance app like Monarch Money or YNAB to make this easy and quick.
What this looks like: Let’s say you make $5,000 a month and spend $3,500 on living expenses and essentials. This leaves you with $1,500, but that doesn’t mean you can afford a monthly payment worth $1,500. In fact, if you use the 20/4/10 rule as a benchmark by spending 10% or less of your monthly income on transportation, you’d want to keep your payment under $500.
2. Use a car affordability calculator. The LendingTree car affordability calculator doesn’t just crunch numbers. It lets you start with the monthly payment you want (the number you calculated in step 1) to show you how much you can afford to spend on your car.
3. Plug in real offers. Once you have a few car loan offers, plug them into the LendingTree auto loan calculator to make sure the monthly payment and total cost of interest fit in your budget.
Remember that owning a car costs money, too. Between fuel, insurance, taxes and repairs, car ownership costs $4,507.11 every year on average. Include these costs in your car budget to make sure your car payment is affordable.
Shop around for your car loan
You’d shop around for flights. Why not your auto loan? LendingTree makes it easy. Fill out one form and get lenders from the country’s largest network to compete for your business.
Tell us what you need
Take two minutes to tell us who you are and how much money you need for your vehicle — we’ll take care of the rest. It’s free, simple and secure.
Shop your offers
We’ll send you offers from up to five trusted lenders. Compare your offers side by side to see which one will save you the most money.
How to save money on a car loan
Buy used or certified pre-owned
Potential savings: Thousands of dollars
Since new cars lose around 20% of their value in the first year alone, you can save thousands on the purchase price by buying a used car instead. If you’re worried you’ll end up with a lemon, consider getting a certified pre-owned car from the manufacturer. These cars are thoroughly inspected and often come with extended warranties.
Want a new car without a long-term commitment? Consider leasing a car for many of the same benefits you get with buying. Lease payments tend to be cheaper than new car payments, and you won’t have to deal with the hassle of selling your leased car or trading it in.
Improve your credit
Potential savings: $2,316 on average (as of publication)
When you improve your credit score from fair to very good, you’ll save an average of $2,316 on your car loan and over $39,000 across different types of credit, like credit cards, personal loans and mortgages. Lenders offer lower rates to borrowers with high scores and a history of on-time payments, which could translate to thousands of dollars of savings across your lifetime.
Look for rebates and deals
Potential savings: Several thousand dollars
Manufacturers sometimes offer special car rebates or discounts to encourage people to buy their cars. Rebates are typically discounts on particular car models or for a specific group of people, like college grads or teachers.
If you have excellent credit, you may be able to snag a 0% APR deal, meaning you won’t have to pay interest on your car loan. It’s unlikely that you’ll be able to combine 0% financing with a rebate, so use our car loan calculator to see which option will help you save more money.
Make a bigger down payment
Potential savings: Hundreds of dollars
It may seem counterintuitive to spend more upfront to save money. But the more you put down for your car, the less you’ll have to borrow — and the less money you’ll pay in interest. Plus, making a larger down payment can help you qualify for a car loan with bad credit.
What sets LendingTree content apart
Expert
Our personal loan writers and editors have 32 years of combined editorial experience and 28 years of combined personal finance experience.
Verified
100% of our content is reviewed by certified personal finance professionals and meets compliance and legal standards.
Trustworthy
We put your interests first. We’ll tell you about any loan drawbacks and be clear about when to consider alternatives.