Car Insurance Resources
How to shop for car insurance, no matter your background or vehicle


Advertising Disclosures
Loading Disclosures…
Your guide to car insurance
Where to get the best deal on car insurance depends on so many things, from your vehicle’s age and value to your driving record and which state you live in. LendingTree created this expert guide to help you find the right coverage at the right price.
Explore types of car insurance
Learn about different types of car insurance so you can find a policy that best fits your needs.
Car insurance rates and insights
Wondering how your car insurance rate compares? Explore average premiums for drivers in your state. Plus, research car insurance trends with LendingTree studies and surveys.
Company reviews
Take a deep dive and read expert LendingTree reviews before choosing a company.
Car insurance for every situation
Teen drivers
Teens can cost a fortune to insure, though getting on a parent’s policy can help lower the price.
Bad credit
Most states allow insurers to charge more for drivers with lower credit scores, so it’s worth doing some research.
Senior citizens
Discounts can help make car insurance affordable for seniors, even as premiums go up for the oldest drivers.
Luxury cars
Car insurance for expensive luxury and vintage vehicles may come at a high price, so shop carefully.
Bad driving record
A speeding ticket or at-fault accident can push your bill sky-high unless you find the right insurer.
Older cars
You can often get a good deal on insurance for your older vehicle, and you might not need as much coverage.
DUI conviction
Comparison shopping is especially important for anyone with a conviction for driving under the influence.
Leased cars
Car insurance strategy can be a little different if you’re planning on leasing your car or truck.
Car insurance rates and market insights
Average car insurance premiums and ratings
Get an overall sense of an insurance company through its average premium and LendingTree rating. LendingTree analyzed thousands of quotes from top insurers to evaluate pricing, customer experience, financial reliability and coverage features.
| Company | Avg. full coverage rate (monthly) | Avg. minimum coverage rate (monthly) | LendingTree rating | |
|---|---|---|---|---|
 | Country Financial | $134 | $61 | 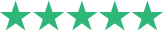 5/5 |
 | Travelers | $135 | $59 | 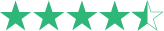 4.5/5 |
 | State Farm | $144 | $56 | 4.5/5 |
 | American Family | $146 | $51 | 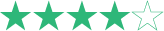 4/5 |
 | Auto-Owners | $154 | $51 | 5/5 |
 | Progressive | $160 | $69 | 4/5 |
 | Geico | $173 | $65 | 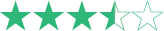 3.5/5 |
 | Nationwide | $190 | $76 | 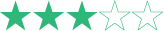 3/5 |
 | Allstate | $248 | $104 | 3/5 |
Be smart: Shop where you live
When it comes to insurance, each of the 50 states (and D.C.) has its own rules. The best car insurance deal for you can be very different from place to place, so it’s worth starting your search with the best companies for your own local area.
Car insurance rates by state
| State | Avg. full coverage rate (monthly) | Avg. minimum coverage rate (monthly) |
|---|---|---|
| Alaska | $153 | $59 |
| Alabama | $135 | $48 |
| Arizona | $201 | $82 |
| Arkansas | $197 | $59 |
| California | $182 | $69 |
| Colorado | $238 | $78 |
| Connecticut | $265 | $128 |
| Delaware | $256 | $116 |
| Florida | $264 | $87 |
| Georgia | $155 | $68 |
| Hawaii | $126 | $46 |
| Idaho | $127 | $45 |
| Illinois | $154 | $61 |
| Indiana | $144 | $53 |
| Iowa | $149 | $36 |
| Kansas | $199 | $64 |
| Kentucky | $176 | $84 |
| Louisiana | $277 | $94 |
| Maine | $107 | $43 |
| Maryland | $172 | $84 |
| Massachusetts | $152 | $70 |
| Michigan | $218 | $78 |
| Minnesota | $194 | $68 |
| Mississippi | $176 | $59 |
| Missouri | $198 | $70 |
| Montana | $183 | $46 |
| Nebraska | $171 | $48 |
| Nevada | $280 | $147 |
| New Hampshire | $113 | $50 |
| New Jersey | $209 | $119 |
| New Mexico | $188 | $66 |
| New York | $192 | $92 |
| North Carolina | $124 | $60 |
| North Dakota | $158 | $43 |
| Ohio | $124 | $48 |
| Oklahoma | $193 | $55 |
| Oregon | $172 | $86 |
| Pennsylvania | $166 | $56 |
| Rhode Island | $224 | $94 |
| South Carolina | $152 | $66 |
| South Dakota | $177 | $31 |
| Tennessee | $150 | $53 |
| Texas | $199 | $79 |
| Utah | $193 | $90 |
| Vermont | $101 | $35 |
| Virginia | $132 | $67 |
| Washington | $188 | $71 |
| Washington, D.C. | $218 | $95 |
| West Virginia | $150 | $56 |
| Wisconsin | $146 | $41 |
| Wyoming | $111 | $27 |
LendingTree car insurance studies and reports
Expert guides
Want to learn more? Here are some short reports on what you should know about car insurance. You can also check out LendingTree’s full guide to comparing car insurance quotes.
How much car insurance costs
Knowing how your rates compare can help you make sure you’re not getting ripped off by your insurance company. And if you have a spotty record, learn how much an accident can raise your insurance bill.
How much car insurance to get
It’s usually wise to get as much car insurance as you can afford, but you may be able to get by with less if finances are tight or if you have an older vehicle.
How car insurance claims work
Filing a claim can be intimidating, but it doesn’t have to be. Find out how car insurance claims work, how to get paid, and when NOT to file a claim in the first place.
Types of car insurance
There’s liability, collision, comprehensive, PIP, gap coverage, and a whole lot more. Learn which kind(s) you need and which you can skip. Learning the difference between full coverage and liability is also a good place to start.
Insurance company reviews
How good is your car insurance, really?
Do you already have insurance but worry you’re paying more than you should be? We have reviews for most of the largest national insurers, with pros and cons for each, as well as comprehensive star ratings. Reviews include:
Or shop around for insurance quotes to compare with what you’re paying now.
How LendingTree helps you find the right policy
Shopping for insurance isn’t always straightforward — especially when availability and pricing can vary widely. LendingTree makes it easier by helping you explore options from multiple insurers, so you can find coverage that fits your needs and budget.
How it works
Tell us about yourself
Answer a few quick questions about your needs.
Compare options from insurers
See quotes and typical rates from insurers that offer coverage in your area.
Choose the right policy
Review your options and pick the coverage that fits your needs and budget.
Frequently asked questions
You need at least the minimum car insurance required by your state. If you have a car loan or lease, you likely also need collision and comprehensive coverage. And leasing typically requires higher liability limits — usually $100,000 per person and $300,000 per accident for bodily injury, and $50,000 for property damage.
Other coverages are optional but can be a good idea, depending on your situation.
It’s a good idea to compare car insurance rates at every renewal, after big life events like getting married or buying a new car or if you experience a large rate increase. You can switch companies at any time.
You can often lower your car insurance bill by comparing quotes from different insurance companies and looking for which ones offer generous discounts. If you find something better, then switch. Otherwise, you might consider raising your deductible, so long as you can afford to pay that higher amount if you wind up in an accident.
Yes, most insurance companies offer coverage for damage you cause while driving a car you don’t own. But if you’re renting a car, you might want to check if your own insurance already covers you. And if you’re borrowing someone’s car, you should check if the owner’s policy already covers you.
No, applying for insurance shouldn’t affect your credit score. Insurance companies use “soft pulls” to check your credit background (which don’t impact your score), rather than “hard pulls” used for loan applications and other purposes.
Yes, you may be able to get a rough estimate on your car insurance rate, though it might not be very accurate. Personal details can have a big effect on your cost. See LendingTree’s report on anonymous car insurance quotes for more info.
If you have a new car, this type of insurance will pay its full replacement value if it gets totaled in an accident (minus your deductible and subject to your policy’s terms). In other words, car depreciation doesn’t reduce your payout. See LendingTree’s guide to new car replacement insurance for more info.
How we create LendingTree ratings
LendingTree rates insurance companies based on several categories. These categories include average rates, discounts, coverage options, third-party customer service ratings and app/website experience. LendingTree weighted these categories based on what customers value in an insurance company.
For third-party customer service ratings, LendingTree includes Complaint Index scores from the National Association of Insurance Commissioners (NAIC) and financial strength ratings from AM Best. NAIC Complaint Index scores are used to determine how satisfied customers are with their claims, while financial strength ratings from AM Best reflect the ability to pay out claims.
See LendingTree’s car insurance ratings methodology and full editorial guidelines for further details.